Screen a rental by checking rent, subtracting operating costs, calculating debt service and testing cash after reserves. The result earns a next step, not purchase approval. Ten minutes organizes a review when inputs are available; it does not replace inspections or due diligence.
Our hypothetical $220,000 house rents for $2,200 a month, meeting the familiar 1% rent-to-price ratio. Yet the worked budget leaves only $73 a month after debt and a replacement reserve. A lower-rent, higher-vacancy case turns that into a loss. The expenses and financing tell you more than the ratio alone.
Minute 1-2: price, rent, and the ratio screen
Record the asking price, the rent you can support, and where that rent came from. An existing signed lease, recent verified lease evidence and an advertised asking rent are different inputs. A listing is a useful comparable; it does not prove that a tenant paid the advertised amount.
Match property type, bedrooms, condition, location, parking, utilities and lease terms. A nearby renovated home with a garage may be a weaker comparison than a similar home farther away within the same rental market. Record any adjustments and the uncertainty they introduce. The rent-pricing guide shows a structured comparison; local rent estimates provide a benchmark to investigate.
Monthly rent divided by price = rent-to-price ratio. For this example, $2,200 / $220,000 = 1.0%. It says nothing about taxes, insurance, repair condition, debt or opening costs. Do not reject or approve every home at an arbitrary 0.7% or 1% boundary. Use the ratio to organize comparable listings, then calculate the actual budget.
If there is an in-place tenant paying $1,800 for the next ten months, a forecast of $2,200 for all twelve months is unsupported. Even if a lawful, achievable $2,200 rent begins for the final two months, scheduled first-year rent would be $22,400, before vacancy or collection losses. Model the lease you acquire before modeling a future market rent.
How it works · illustrated
A quick analysis should produce a decision and a reason. Missing evidence and a documented failure require different next steps.
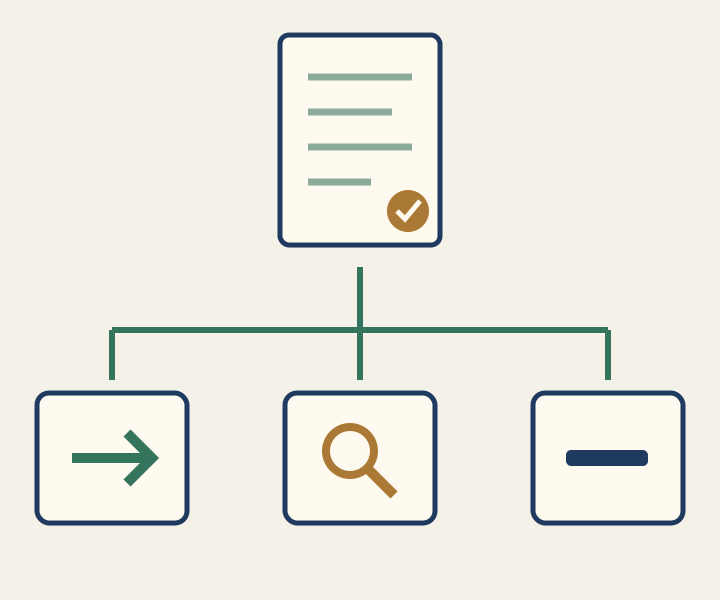
- The evidence supports more work
- Proceed
The base case meets your criteria and you can fund the modeled downside. Begin full due diligence.
- A material input is unresolved
- Investigate
Name the missing quote, document or approval and the person who will obtain it.
- A verified constraint breaks the plan
- Pass
The proposed use, supported income or required cash conflicts with your stated criteria.
Proceed does not mean buy. A preliminary model cannot establish property condition, legal use, insurance coverage or loan approval.
Original RentalCalcs illustration · Reviewed October 14, 2026. Conceptual artwork, not a monetary scale. The surrounding article supplies the assumptions and sources.
An unknown that can change the decision belongs on an investigation list. Do not quietly replace it with zero or a precise-looking estimate. The screen should say “insurance quote pending” when the coverage and price have not been established.
Minute 3-5: the six expense lines that matter
Start with six budget areas: taxes, insurance, repairs, management, other owner-paid operating costs and replacement reserves. Vacancy reduces income before those costs. Keep replacements below net operating income so the distinction between operations and cash funding remains visible.
Preview: 3 of 6 rows
| Budget area | Evidence to obtain | Why the shortcut can fail |
|---|---|---|
| Property taxes | Parcel record and local assessor guidance on changes, exemptions and timing | The seller's bill may reflect an exemption or valuation that will change |
| Insurance | Quote for the intended rental use, limits, exclusions and deductibles | The listing's homeowner premium may not describe your coverage |
| Routine repairs | Inspection findings, maintenance history and a scoped annual allowance | A low percentage cannot make known work disappear |
| Management and leasing | Written fee schedule, including minimums, placement and renewal fees | A collection-based fee differs from a gross-rent charge |
| Other owner-paid operations | HOA, utilities, licenses, lawn/snow, accounting and applicable local charges | A blank field is not evidence of a zero bill |
| Replacement reserve | Condition and remaining life of roof, HVAC and other major components | A reserve contribution is not the same as a current repair expense |
In the example, annual scheduled rent is $26,400. A 5% vacancy-and-credit-loss allowance leaves $25,080 effective income. We assume $3,300 taxes, $1,500 insurance, $2,112 routine repairs and management at 8% of collected rent, or $2,006. There is no HOA, owner-paid ongoing utility bill, other income or separate leasing fee in this simplified scenario. Add those costs when the actual property or management agreement requires them.
Operating costs are therefore $8,918, leaving $16,162 NOI. Net operating income is effective income less operating expenses, before loan payments, income tax and the separately modeled capital reserve. The additional $2,112 annual replacement contribution is a cash allocation after NOI, not another routine-repair bill. Both $2,112 allowances are hypothetical; neither is a property inspection or a market benchmark.
The OCC's commercial real estate lending handbook discusses income, expenses, underwriting and sensitivity analysis. Its supervisory framework is useful context, not a promise that a residential lender will use our definitions. Lenders can adjust income and expenses, including replacement allowances, differently.
For a complete operating forecast, use the pro forma guide. For a rough expense-ratio cross-check, see why the 50% rule cannot substitute for quotes and records.
Minute 6-7: debt service at the quoted rate
Use the offered loan amount, interest rate, term, amortization and fees. Check whether the rate is locked, whether payments change, and whether a balloon or interest-only period matters. A modeled payment is not an available loan.
Here we assume 25% down, leaving a $165,000 loan at a hypothetical 7% fixed rate with 30-year amortization. Principal and interest are $1,098 a month, or $13,173 a year. The calculations use the unrounded annual amount of $13,172.989405.
We already deducted property taxes and insurance in the operating budget. Subtract only principal and interest here. Subtracting full PITI as well would count tax and insurance twice. Conversely, subtracting only mortgage interest would miss the principal cash payment.
Our NOI divided by annual principal and interest is 1.23. That is this example's coverage calculation, not a lender approval. A lender may use different rent, deductions or a different debt-service denominator. Use the DSCR explanation to compare definitions before comparing ratios.
Minute 8-9: cash flow, cap rate, cash-on-cash
These metrics answer different questions. Cap rate describes operating income relative to price. Cash flow measures what remains after the modeled cash obligations. Cash-on-cash divides an explicitly defined annual cash amount by the capital committed to earning it.
The worked decision · Hypothetical dollar amounts
Each bar shows the annual money remaining after the next deduction. These balances are sequential and should not be added together.
After vacancy and credit loss$25,080
$26,400 scheduled rent less the 5% income-loss assumption.
After operating costs: NOI$16,162
Subtract taxes, insurance, routine repairs and management.
After principal and interest$2,989
Subtract $13,173 in annual scheduled loan payments.
After replacement reserve$877
Subtract the $2,112 capital contribution: about $73 per month remains.
All bars start at zero on the same $0–$26,400 scale. Operating costs exclude the replacement reserve. The assumed $220,000 price and $2,200 monthly rent do not establish a profitable investment by themselves.
Original RentalCalcs calculations · Reviewed October 14, 2026. Values, units and assumptions are also live text and appear in the adjacent budget. Color is not needed to interpret the result.
Open the rental screening worksheetThe result is $877 a year, about $73 a month, after principal, interest and the $2,112 replacement contribution. The 1% rent ratio has not produced a large cash cushion.
Preview: 3 of 8 rows
| Annual calculation | Amount | Meaning |
|---|---|---|
| Scheduled rent | $26,400 | $2,200 for twelve months |
| Vacancy and credit loss | -$1,320 | 5% of scheduled rent |
| Effective income | $25,080 | Before operating costs |
| Operating costs | -$8,918 | Taxes, insurance, repairs and management |
| NOI | $16,162 | Before financing and replacement reserve |
| Principal and interest | -$13,173 | Full scheduled loan payments |
| Replacement reserve contribution | -$2,112 | Cash set aside for future capital work |
| Cash after debt and reserve | $877 | Before personal income tax |
The exact NOI is $16,161.60 and annual cash after the reserve is $876.610595. Rounded rows may not sum exactly. For the return measures:
- Cap rate: 7.3%. Divide NOI by the $220,000 purchase price. This version excludes the replacement reserve and financing; it does not measure your spendable return.
- Cash after debt and reserve: $73 per month. This is a stabilized annual average, not a guarantee that every month has positive cash.
- Cash-on-cash: 1.1% on total committed cash. We use $55,000 down, $6,600 closing costs and prepaids, $750 inspection, $4,000 initial work and $10,000 retained reserves: $76,350 in total.
The retained $10,000 is still your asset. Including it in this denominator makes the capital commitment explicit. A calculation excluding that reserve uses $66,350 and returns about 1.3%; do not compare the two without disclosing the basis. These returns exclude appreciation, principal-paydown gains and tax benefits. See the cash-on-cash guide for that distinction.
This example assumes the stabilized rental year starts after the initial work. It has no separate lease-up carrying allowance in its $76,350 funding budget. If you must carry the property before that year begins, add those payments and any extra costs. The first-rental funding guide models that opening period separately.
The downside case changes the decision
Reduce rent by 5% to $2,090 and increase vacancy-and-credit loss from 5% to 10%. Effective income falls to $22,572. Management falls with collections, but taxes, insurance, routine repairs, debt service and the replacement contribution stay at their base amounts.
That leaves -$1,431 a year, or -$119 a month, after debt and reserve. This replaces the original vacancy assumption; it is not a second vacancy deduction on top of it. If your plan requires $200 a month of positive cash, neither scenario meets it. A supported price or cost change could alter the result; hoped-for appreciation does not pay the monthly shortfall.
As a conditional negotiation check, the base operating budget supports about $194,558 of purchase price at 25% down and the same 7% loan if the goal is $200 monthly after the reserve. That solves for allowable debt service of $11,649.60 a year. It holds rent, tax, insurance and other costs fixed; it is not an appraisal, an offer recommendation or proof the seller will agree.
Minute 10: the five decision questions
- Is the rent supported and available when modeled? Review leases, concessions, arrears and comparable evidence. An occupied property may carry contractual income below the advertised potential.
- Can the property be used as proposed? Confirm legal units, rental licensing, HOA restrictions and material approval requirements for the address. A profitable spreadsheet cannot establish a permitted use.
- Can the costs be funded and insured? Identify work needed before occupancy, deductibles and binding coverage conditions. NFIP guidance says flood insurance is required for properties in a Special Flood Hazard Area with a government-backed mortgage; lenders may require it elsewhere too. A map lookup alone is not an insurance quote.
- Do the loan and total cash commitment fit? Compare the actual terms, closing budget and retained liquidity. The insurance cost guide and funding worksheet help fill the gaps that a loan-payment estimate misses.
- What happens when the largest uncertainty goes against you? Test the uncertain rent, vacancy, repair or insurance cost. Use the break-even occupancy guide when collections are the deciding input.
An unresolved material question means investigate. A documented conflict with your budget or required use can mean pass. A supported base case and an affordable downside can justify proceeding to full due diligence. These outcomes should remain distinct.
When a 10-minute pass earns a full analysis
Carry the evidence and unresolved questions into the rental screening worksheet, then build the detailed scenario in the rental property calculator. Record an owner and a next action for each missing item: obtain the insurance quote, inspect the roof, review the lease or confirm the loan terms.
The current calculator's expense conventions include a capital reserve within operating expenses. This article shows it below NOI. For the same inputs, adding that reserve back to the tool's NOI reconciles the presentation; do not deduct it again from cash flow. Its cash-on-cash denominator also uses total cash required, so reconcile prepaids, initial work and retained funds before comparing returns.
The deeper review should replace assumptions with documents and dates, then revisit the decision. A quick positive result is useful only if the rent, expenses, funding and permitted use survive that work.
Get new articles and market updates
Investing guides and market data, straight to your inbox. Unsubscribe anytime.
