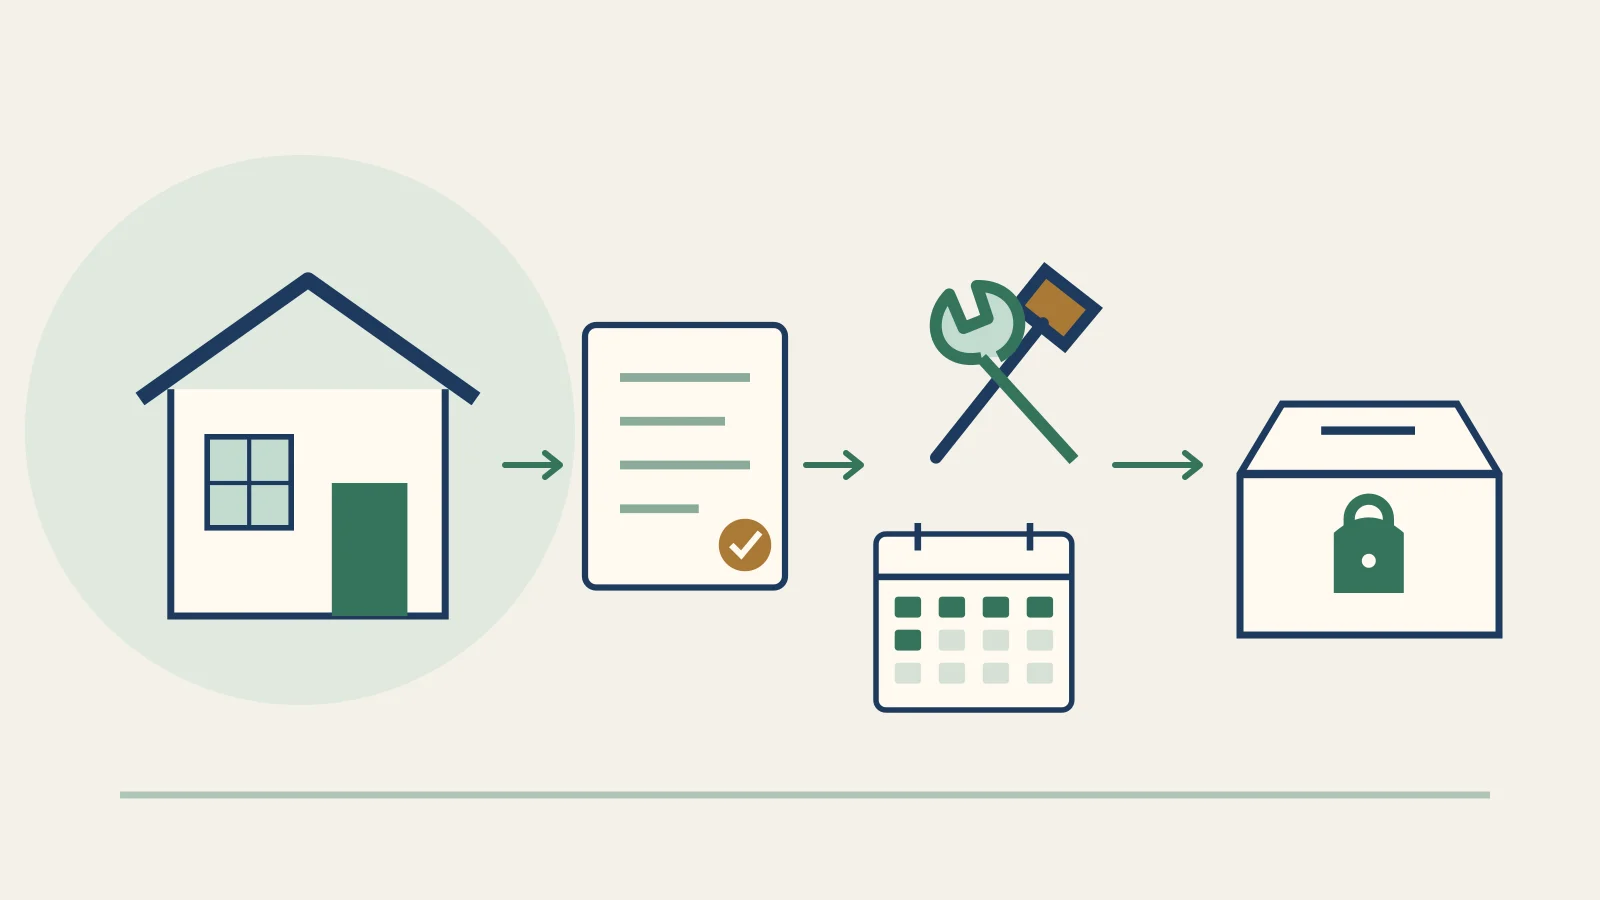
The down payment is only part of a first rental's funding. In our hypothetical $250,000 purchase, $50,000 down becomes $77,395 in total funding after transaction costs, initial work, lease-up time and a separate cash reserve. Budget all five before shopping.
That is an example, not a universal percentage of the price. A tenant already in place, a different loan, major repairs or expensive insurance can move the total substantially. Start with the actual property and payment dates, then decide whether the cash you have is enough.
The full funding budget, not just the down payment
There are three different numbers to write down: total money committed to the purchase, the remaining amount due at settlement, and money available after the property opens. Calling all three “cash to close” hides the distinction that matters most to a new owner.
Total funding = down payment + transaction costs + initial work + planned carrying costs + retained reserve. Inspection and other costs paid before settlement belong in that total too. A deposit already credited toward the purchase belongs in the down payment or closing calculation; it is not an extra cost on top.
Suppose the $250,000 example has a $50,000 down payment and $7,500 of closing costs and prepaids. That is $57,500 allocated to settlement before credits. If you already paid a $5,000 earnest-money deposit that is fully credited at closing, the remaining settlement amount is $52,500, before any other adjustments. The $750 inspection is paid separately in this example.
The deposit changes when you provide the money, not the total funding requirement.
For loans that use the consumer Closing Disclosure, its cash-to-close section reconciles deposits, credits and adjustments. The CFPB's Closing Disclosure explainer shows where to check them. Business-purpose investment financing may use different documents; ask for an itemized settlement estimate and compare it with the final statement.
How it works · illustrated
For the hypothetical $250,000 purchase, money moves through three different stages. The reserve remains available after the modeled opening costs.
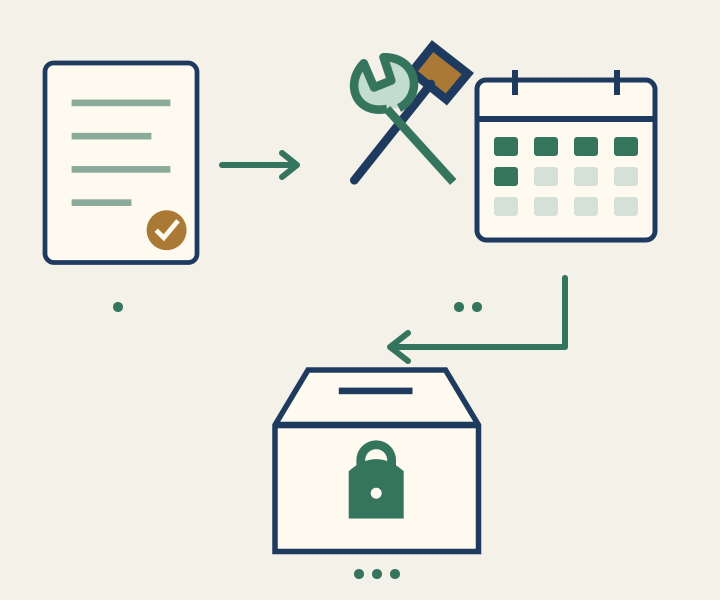
- 1 · Complete the transaction
- $58,250
$50,000 down, $7,500 closing and prepaids, plus $750 inspection. A credited deposit is part of this amount.
- 2 · Prepare and open
- $8,911
$5,000 initial work plus two PITI payments and $500 utilities before rent starts.
- 3 · Retain the buffer
- $10,234
Six modeled PITI payments remain available after the planned opening period.
Total funding is $77,395. These are separate uses of money; the retained reserve is not spent at settlement. Assumptions and rounding are detailed below.
Original RentalCalcs illustration · Reviewed October 14, 2026. Conceptual artwork, not a monetary scale. The surrounding article supplies the assumptions and sources.
The reserve is an asset you retain, not a bill you pay to the seller. A $10,000 balance cannot simultaneously be your roof budget, the funds for an expected two-month vacancy and an untouched $10,000 emergency buffer. Assign known spending first. Then measure what is left.
Down payment by loan type: conventional, FHA house hack, DSCR
How much down for a rental property depends on the program, occupancy, units and borrower. A minimum down payment is an eligibility boundary, not a complete financing quote.
| Financing route | Useful starting point | What still needs confirmation |
|---|---|---|
| Fannie Mae standard DU investment purchase, one unit | Maximum 85% loan-to-value, equivalent to 15% down when value supports the price | Borrower, property, mortgage insurance and lender requirements |
| Fannie Mae standard DU investment purchase, two to four units | Maximum 75% loan-to-value, equivalent to 25% down on the same basis | Loan eligibility, reserves, rental income and lender conditions |
| FHA owner-occupied purchase | HUD advertises down payments as low as 3.5% for eligible buyers | Actual occupancy, mortgage insurance, property and borrower eligibility |
| DSCR or other business-purpose loan | Use a written program quote; there is no single minimum across lenders | Down payment, coverage definition, reserves, fees and prepayment terms |
The conventional figures come from the August 5, 2026 Fannie Mae eligibility matrix for standard Desktop Underwriter purchase loans. They do not describe every conventional program or guarantee approval. If the appraisal is below the price, the buyer may need additional cash.
HUD's FHA loan overview describes the low-down-payment option. It is not permission to finance a non-owner-occupied investment as a primary residence. For the owner-occupancy decision and costs of living in one unit, use the house-hacking guide and duplex-versus-triplex comparison.
Ask for quotes on the same property with the same loan term, lock period, points and occupancy. A larger down payment reduces borrowing, but whether it improves the offered rate or removes another cost depends on the quote. The DSCR-versus-conventional comparison explains the financing tradeoff in more detail.
For the broader program comparison, use the investment-property down payment guide. Here, the next step is to fund everything beyond that down payment.
Closing costs, reserves, and the numbers buyers forget
Build the transaction budget from line items: lender and title charges, recording or transfer costs, prepaid interest, required insurance, escrow funding and any points. Our examples use 3% of price as a combined allowance, not a national average or a quote. They exclude the separately listed $750 inspection. Replace both estimates with property-specific amounts.
Prepaid insurance and tax escrows affect cash timing. They do not make taxes and insurance disappear from the operating budget. Equally, paying a premium at closing is not a reason to expense that same annual policy twice. Reconcile the settlement statement, policy period, escrow deposits and scheduled payments. The rental insurance guide covers the quote details worth comparing.
There are also two different reserve questions. What assets does the lender require after closing? And what accessible cash does your operating plan require?
Under Fannie Mae's minimum reserve requirements, DU investment-property transactions generally require six months of reserves, with possible additional requirements for other financed properties. The program's qualifying payment and eligible assets govern that calculation. Six months of PITI in our example is a simplified planning assumption, not a promise that the loan qualifies or the property is adequately funded.
For your own budget, list the expenses that continue before the first rent arrives: mortgage payments, utilities, lawn or snow service, licensing, leasing charges and work needed for occupancy. Add any costs that apply to the actual home. Keep personal emergency savings outside the amount you commit to the property.
Worked totals: a $150,000, $250,000, and $400,000 purchase
These are original hypothetical scenarios reviewed October 14, 2026. Each uses 20% down, a 7% fixed rate over 30 years, no points, no mortgage insurance and no HOA. The interest rate is a modeling input, not a current loan offer. Taxes and insurance together equal an assumed 1.8% of price per year.
We fund two full scheduled PITI payments before rent starts, plus $250 of owner utilities in each month. PITI means principal, interest, taxes and insurance. The six-month reserve remains available after that planned lease-up period. Actual closing dates, escrow timing, work schedules and first-payment dates will change this calendar.
The worked decision · Hypothetical dollar amounts
Three separate allocations make up the total. The last allocation remains your cash; it is not a transaction expense.
Transaction, including inspection$58,250
Down payment, closing/prepaids and the separate inspection.
Initial work and planned lease-up$8,911
Preparation plus two PITI payments and $500 utilities.
Cash retained after opening$10,234
Six modeled PITI payments, still available afterward.
All bars start at zero on the same $0–$80,000 scale. Values are portions of one total, rounded from unrounded calculations. The retained reserve follows the two-month opening allowance.
Original RentalCalcs calculations · Reviewed October 14, 2026. Values, units and assumptions are also live text and appear in the adjacent budget. Color is not needed to interpret the result.
Open the first-rental funding worksheetThe middle example needs $77,395 total, of which $10,234 remains reserved after the modeled purchases, initial work and two months of carrying costs. The table rounds only for display; totals use unrounded loan payments.
Preview: 3 of 8 rows
| Funding item | $150,000 price | $250,000 price | $400,000 price |
|---|---|---|---|
| Down payment, 20% | $30,000 | $50,000 | $80,000 |
| Closing costs and prepaids, 3% allowance | $4,500 | $7,500 | $12,000 |
| Inspection paid separately | $750 | $750 | $750 |
| Initial work before leasing | $3,000 | $5,000 | $8,000 |
| Two PITI payments plus $500 utilities | $2,547 | $3,911 | $5,958 |
| Six PITI payments retained as reserve | $6,140 | $10,234 | $16,374 |
| Total funding | $46,937 | $77,395 | $123,082 |
| Monthly PITI, a reference rather than another upfront cost | $1,023 | $1,706 | $2,729 |
Scroll the table sideways for more columns.
For the $250,000 home, the $200,000 loan has a $1,331 monthly principal-and-interest payment. Assumed monthly tax and insurance funding adds $375. The exact PITI used in the calculations is $1,705.604990; the unrounded total is $77,394.839923. This precision is only for checking the arithmetic, not a forecast accurate to cents.
These funding totals are about 31% of price because of the assumptions we chose. That does not establish a “31% rule.” A $20,000 roof would matter much more than the small differences between the displayed percentages.
What happens if the opening slips?
Take the middle example after its planned two-month lease-up allowance is spent. An extra $5,000 repair and one additional vacant month with PITI plus $250 utilities consume another $6,956. The retained reserve falls from about $10,234 to $3,278. That is less than two more months of the same PITI-and-utilities budget.
This additional month is beyond the two already funded; we have not charged the same delay twice. A reserve can absorb the modeled surprise, but it no longer provides its original protection. Decide whether you would replenish it, reduce the price or pass before relying on the optimistic opening date. The break-even occupancy guide helps connect vacancy to the ongoing budget.
Ways to lower the entry cost that actually work
A lower price cuts the down payment and loan balance. It does not automatically cut the insurance quote, repair bill or assessed tax obligation by the same proportion. Compare properties with their actual costs.
Seller contributions may pay eligible transaction costs. Fannie Mae's interested-party contribution rules limit financing concessions on investment properties to 2% of the lower of price or appraised value, subject to actual eligible costs and program conditions. They cannot fund the down payment or required reserves.
At a supported $250,000 value, a permitted $5,000 credit could reduce eligible closing cash; it does not turn into $5,000 of unrestricted money for repairs.
An owner-occupied purchase may use different financing, but it also changes the living arrangement and which units generate rent. Compare the complete house-hacking budget, including your own housing costs.
A different down payment trades liquidity for debt service. On our $250,000 example, increasing down payment from 20% to 25%, with the same hypothetical rate and all other assumptions, reduces monthly principal and interest by $83.
Total funding rises from $77,395 to $89,230. The extra funding is $11,835 rather than $12,500 because the modeled carrying costs and six-payment reserve also fall. Neither option is automatically better: compare the offered loan terms, ongoing cash flow and cash left outside this purchase.
Ways that sound clever and end badly
The weak plan is one that makes a cost disappear on paper. Skipping a repair allowance does not repair the house. Calling planned vacancy an emergency does not leave an emergency fund intact. Assuming a refinance will restore every dollar does not create a lender commitment.
Document any borrowed funds, gifts or partner contributions with the lender before relying on them. Eligibility and repayment obligations depend on the program. If the deal works only with funds the lender will not accept, it is not a funded purchase.
Use the first-rental funding worksheet to assign every dollar to a payment date or retained balance. Then run the property's ongoing income and expenses in the rental property calculator. A budget that closes the purchase can still produce poor cash-on-cash returns.
Keep the worksheet beside the calculator. Its current reserve-month calculation is not six full PITI payments, and its cash-required output separately estimates prepaids. Reconcile those lines instead of copying our combined 3% closing-and-prepaids allowance and adding prepaids again. The worksheet's inspection, opening calendar and retained balance should remain explicit. When that funding budget works, the 10-minute rental analysis tests whether the income case deserves deeper work.
Get new articles and market updates
Investing guides and market data, straight to your inbox. Unsubscribe anytime.
