Break-even occupancy measures how much potential rent must be collected to cover costs. Start with annual operating expenses plus debt service, divided by annual gross potential rent. Then include capital reserves in a second threshold for the owner's cash budget.
The important distinction is between units occupied and dollars collected. A fourplex with three occupied units has 75% physical occupancy, but its collection rate depends on which unit is empty, the rents, concessions and unpaid balances. In the example below, the property needs 83.4% of potential rent to cover operations, financing and its planned capital reserve. That is a budget result, not a universal safe target.
What break-even occupancy tells you that cash flow does not
A cash-flow projection answers what happens at the occupancy and rent you entered. A break-even calculation asks how far income can fall before that result reaches zero. Read them together: a positive annual forecast can still conceal a difficult vacancy month or a large repair due before the rent arrives.
Use a consistent one-year period and label the denominator. This guide's collection share means rent collected for that period divided by the full year's potential rent at the modeled rents. It captures vacancy, concessions and credit loss together. Property reports may use different economic-occupancy conventions, so reconcile their definitions before comparing ratios.
Physical occupancy counts occupied units. A resident who has not paid is still physically occupying the home; the missing payment reduces collections. Do not relabel that resident as a vacancy, and do not subtract the same loss again in the expense section.
How it works · illustrated
This separate unequal-rent illustration has four units totaling $5,600 a month. The $1,600 unit is empty; the other three pay in full.
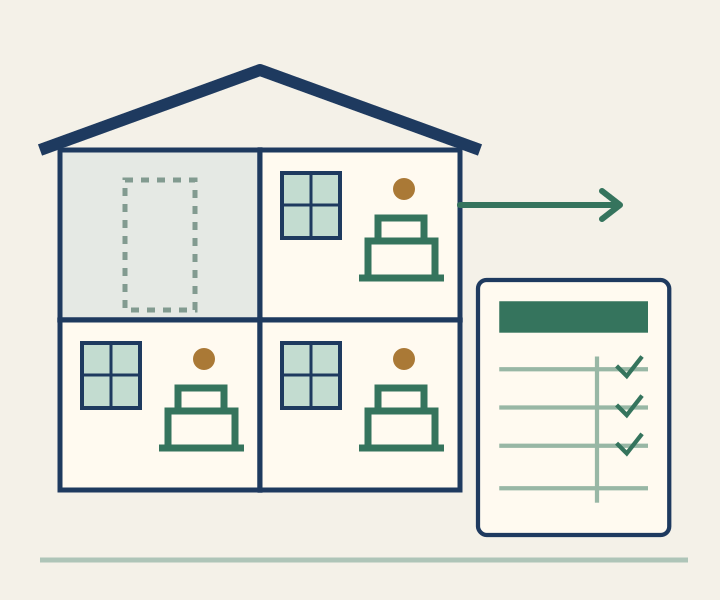
- Physical occupancy
- 3 of 4
Three occupied units mean 75% physical occupancy.
- Rent collected
- $4,000
$1,400 + $1,300 + $1,300 received for the month.
- Share of potential rent
- 71.4%
$4,000 collected divided by $5,600 potential rent.
The vacant unit carries more than one-quarter of the rent. Concessions and unpaid rent could lower collections further without changing the occupied-unit count.
Original RentalCalcs illustration · Reviewed October 14, 2026. Conceptual artwork, not a monetary scale. Sources and hypothetical assumptions appear in the surrounding article.
Consider four rents totaling $5,600 per month: $1,600, $1,400, $1,300 and $1,300. If the $1,600 unit is empty and all other rent is paid, collections are $4,000, or 71.4% of potential rent. If a $1,300 unit is empty, collections are $4,300, or 76.8%. Physical occupancy is 75% in both cases. A generic one-unit vacancy test misses that difference.
Start with the actual rent roll and collections, then use the rental pro forma guide to keep current records separate from a future stabilized forecast.
The formula: expenses plus debt service over gross potential rent
The common screening formula is:
Break-even occupancy ratio = (annual operating expenses + annual debt service) / annual gross potential rent.
Multiply by 100 to express the ratio as a percentage. A result above 100% means the modeled rent cannot cover the included costs even with full collections; eliminating vacancy alone cannot solve that deficit.
Gross potential rent is the rent available with every unit paying the modeled rent for the full period, before vacancy and concessions. Debt service includes principal and interest. Income taxes, depreciation and changes in property value are outside this cash break-even test.
The simple ratio holds the entered expense budget constant as income falls. That is useful for screening, but some costs change with collections. If management costs 8% of collected rent, reduce that fee as collections fall instead of charging the full-occupancy fee at every scenario.
For a model with one proportional expense and no other income:
Collection share needed = (fixed operating costs + debt service + chosen capital reserve) / [gross potential rent x (1 - variable expense share)].
Here, "fixed" means held constant in this scenario, not guaranteed never to change. Repairs can be irregular; management contracts can have minimum fees, leasing charges or renewal charges. Those terms belong in the model. A flat management minimum cannot be represented by a simple percentage at every occupancy level.
Preview: 3 of 6 rows
| Input | Include | Avoid |
|---|---|---|
| Potential rent | Unit-level monthly rent multiplied by the months available | Already vacancy-adjusted income in the denominator |
| Fixed operating costs | Taxes, insurance, modeled routine repairs and owner-paid services | Counting principal or a capital reserve as ordinary operations |
| Variable costs | Fees that actually change with rent collected | Assuming every expense disappears when a unit is vacant |
| Debt service | Scheduled principal and interest over the same year | Interest alone on an amortizing loan |
| Capital reserve | A separate planned replacement contribution | Counting both that contribution and the same funded replacement as two costs |
| Other income | Only the amount credible in the downside being tested | Treating parking or laundry as occupancy-independent without evidence |
If separate income truly continues through the modeled vacancy, subtract its net contribution from the numerator. If it falls with occupancy, model that relationship explicitly. The worked example excludes other income so its denominator is unambiguous.
Our NOI definition guide explains the operating-cost boundary. The OCC's commercial real estate lending handbook also emphasizes defined income/expense assumptions and the difference between modeled NOI and actual cash flows. Lender reserve conventions can differ from the convention used here; this article is not a lender approval test.
Worked example: a fourplex at 100, 90, and 75 percent occupancy
This hypothetical fourplex costs $520,000, with 25% down and a $390,000 loan. The illustration assumes a fixed 7% annual rate, monthly payments and 30-year amortization. This is an assumption, not a current loan quote. Principal and interest are $2,594.68 per month, or $31,136.16 per year, calculated before rounding.
Each of the four units rents for $1,400 per month, giving $67,200 annual potential rent. The modeled fixed operating costs total $18,000: $7,200 property tax, $3,600 insurance, $3,600 routine repairs, $2,400 owner-paid utilities and $1,200 grounds/services. Management is 8% of rent collected. The owner also budgets $2,400 annually for capital replacements. No other income, acquisition work, income tax or appreciation is included.
Preview: 3 of 8 rows
| Annual result | 100% collected | 90% collected | 75% collected |
|---|---|---|---|
| Rent collected | $67,200 | $60,480 | $50,400 |
| Management at 8% | $5,376 | $4,838.40 | $4,032 |
| Fixed operating costs | $18,000 | $18,000 | $18,000 |
| NOI before debt and reserve | $43,824 | $37,641.60 | $28,368 |
| Debt service | $31,136.16 | $31,136.16 | $31,136.16 |
| Cash before capital reserve | $12,687.84 | $6,505.44 | -$2,768.16 |
| Capital reserve contribution | $2,400 | $2,400 | $2,400 |
| Cash after debt and reserve | $10,287.84 | $4,105.44 | -$5,168.16 |
Scroll the table sideways for more columns.
With no capital reserve, the variable-expense formula gives 79.5%. Adding the $2,400 reserve raises the required collection share to 83.4%: ($18,000 + $31,136.16 + $2,400) / ($67,200 x 92%). The simple ratio using full-occupancy operating costs gives 81.1% before reserves because it does not reduce the management fee at lower collections. These are different assumptions, not competing answers to the same model.
The worked decision · Hypothetical annual scenario
The equal-rent fourplex needs 83.4% of its $67,200 potential rent to cover the modeled operating costs, loan and $2,400 reserve.
All modeled rent collected100%
$10,288 annual cash after debt and reserve
The 90% collection forecast90%
$4,105 annual cash after debt and reserve
Reserve-inclusive break-even83.4%
$0 cash after debt and reserve
One equal-rent unit empty all year75%
-$5,168 annual cash after debt and reserve
All bars start at zero on the same 0–100% collection scale. Management is 8% of collections; fixed operating costs are $18,000 and annual debt service is $31,136.16. Dollar labels round the unrounded calculations.
Original RentalCalcs calculations · Reviewed October 14, 2026. All values and assumptions are available as text and in the adjacent table. No color interpretation is needed.
Open the collection and vacancy worksheetAt 90% collections, the reserve-inclusive cushion is only 6.6 percentage points, not 16.6. The latter is the gap from perfect collections. A 90% collection forecast means the plan has already used part of the theoretical margin.
Four equal-rent units create 48 potential unit-months each year. A 16.6% loss allowance is roughly eight equivalent unit-months. That translation is valid only if losses are all vacancy, rents are equal, and the other assumptions stay constant. It is not permission to ignore credit loss, concessions or turnover bills. One empty unit for a full year loses 12 unit-months and produces the 75% column above.
What a safe margin looks like by property size
There is no occupancy percentage that makes every property safe. A lower threshold leaves more room under the stated assumptions, but it does not describe the condition of the roof, the timing of taxes or the reliability of a rent estimate.
Start with the loss of an actual tenant rather than an abstract five-point change. In equal-rent buildings, one vacant unit removes 50% of potential rent in a duplex, 25% in a fourplex and 10% in a ten-unit property during that vacancy. Unequal rents change the income impact. Larger properties can also have simultaneous lease expirations or a common problem affecting several units.
Compare three things: your expected collection share, the reserve-inclusive threshold and the cost of the specific downside. Then decide how much accessible cash is needed for that downside. The cash-on-cash guide helps connect annual cash flow with the equity committed, while the DSCR guide addresses debt coverage under a different denominator.
Single family's brutal version: occupancy is 0 or 100
A single home is physically occupied or empty at a point in time, but annual rent collections can take any value between those extremes. Budget both the annual result and the cash needed during a vacant month.
For illustration, a $280,000 home with 25% down has a $210,000 loan. At the same hypothetical 7%, 30-year terms, annual principal and interest total $16,765.62. Assume $2,400 monthly rent, $6,600 fixed annual operating costs, management at 8% of collections and a $1,200 annual capital contribution. Its reserve-inclusive collection threshold is 92.7%. Even one whole month without rent leaves only 91.7% of annual potential rent, before any other losses.
With no rent, its scheduled monthly debt payment and modeled fixed costs total $1,947.14. Maintaining the $100 reserve contribution brings the planned monthly outflow to $2,047.14. Three such months plus a separate $3,000 turnover bill require approximately $9,141. That is a scenario funding requirement, not a universal recommended reserve. Taxes, insurance and repairs may come due in larger installments, so map the actual payment calendar.
The insurance cost guide and management cost comparison help source two inputs that are easy to understate. Self-management can change the cash fee, but your time and leasing obligations remain.
Stress-test the downside before you offer
Run rent and collection stress together. In the fourplex below, "90% collected" means 90% of the potential rent at that column's rent level. All values are annual cash after debt and the $2,400 reserve, rounded to dollars; fixed costs and loan terms stay unchanged.
| Rent paid | Original rents | Rents 5% lower | Rents 10% lower |
|---|---|---|---|
| 100% | $10,288 | $7,197 | $4,105 |
| 90% | $4,105 | $1,323 | -$1,459 |
| 80% | -$2,077 | -$4,550 | -$7,023 |
| 75% | -$5,168 | -$7,487 | -$9,805 |
Scroll the table sideways for more columns.
The combined 90%-collection/10%-rent-decline case turns a positive base case negative. Separately test a tax or insurance increase, a documented repair and the actual vacancy/turnover period. A fixed loan's payment does not rise simply because market rates rise; rate stress belongs at an adjustable-rate reset, new loan or refinance.
Use the break-even worksheet to record rent-roll evidence, cost assumptions, losses and the cash calendar. Then enter an actual property in the single-family rental calculator for one-to-four-unit rental analysis, or the multifamily calculator for a larger property.
Our current multifamily break-even result uses entered operating expenses plus debt service over potential rent plus other income; it does not solve the variable-management equation shown here. Reconcile reserves and other-income treatment before comparing results.
For a fuller downside matrix, follow the rental sensitivity guide. The useful conclusion is specific: which loss makes this property cash-negative, how much cash it would consume, and whether your documented reserve can fund that period.
Get new articles and market updates
Investing guides and market data, straight to your inbox. Unsubscribe anytime.
