Underwrite a duplex or 2–20 unit apartment building. Enter rent, expenses and financing to estimate cash flow, NOI, cap rate and DSCR. Unlimited analysis, no account required.
Published by RentalCalcs · Content and usability reviewed .
Data periods and program effective dates are shown separately. Report a correction.
Unlimited free property analysis. No account required.
Monthly CF
$0
Cash-on-Cash
0.0%
Cap Rate
0.0%
DSCR
0.00x
Start with the location
Pick the market and we fill local property tax and insurance rates for you.
$
%
$
%
%
%
$0
$0
$
$
%
%
$
$
%
%
%
$
$
Quick-Fill Assumptions
Using moderate assumptions
Used for 5-year projections. Adjust based on your market expectations.
%
%
%
Deal Analysis
Untitled Deal
Monthly Cash Flow Before Tax
$0.00
$0 / year
After modeled expenses, CapEx reserves and debt payments.
Key Metrics
Cap Rate
0.0%Target: > 6%
Cash-on-Cash
0.0%Target: > 8%
DSCR
N/ATarget: > 1.25
GRM
0.0Target: < 10
Break-even Occupancy
0%Target: < 85%
Targets are screening references, not loan approval criteria.
Quick Stats
Price per Unit$0
Rent per Unit$0/mo
NOI per Unit$0/yr
Cash Flow per Unit$0/mo
Expenses per Unit$0/yr
Total Cash Required$0
Loan Amount$0
Upgrade to Pro for professional reports, portfolio tools, and more
List your rental free on VoucherMatch and reach voucher holders searching your market. Every application shows the voucher type and household size up front.
Start with the asking price, the building's total monthly rent and a loan quote. Use Quick Analysis for a first pass, then Full Underwriting to review the rent roll, itemized costs and financing. Keep current operations separate from hoped-for rent increases.
Set the unit count. Model a duplex, triplex, quadplex or a 5–20 unit apartment building. In Simple income mode, enter rent for the whole building, not per unit.
Check occupied and vacant units. Rent Roll mode sums current rents for occupied and notice units; vacant units contribute $0. Vacancy and credit loss percentages then reduce that rent further. Treat the vacancy percentage as an additional allowance in this mode, so you do not count the same vacancy twice.
Choose an expense method. Quick Estimate applies one percentage to effective gross income after vacancy and credit loss, including other income. Its expense categories are estimates. Itemized mode uses your annual taxes, insurance, utilities and other costs; percentage management, repairs and CapEx also use effective gross income.
Enter cash and debt costs. Include down payment, closing costs, loan points and initial rehab. Basic financing uses a fully amortizing loan. The examples below do not include mortgage insurance, interest-only periods, balloon payments or renovation financing.
If you will live in a unit, use the house hacking calculator to separate your housing cost from tenant income. For residential loan options on a 1–4 unit investment, see the rental property calculator.
Duplex and eight-unit apartment examples
These fixed examples use the same calculations as the tool. Both assume all units are rented, 5% vacancy, no credit loss or other income, 25% down, 3% closing costs, and a 7% loan amortized over 30 years. Loan points and initial rehab are $0; advanced financing and value-add are off. These are illustrations, not loan offers or market benchmarks. Editing your deal above does not change them.
Duplex: itemized expenses
$350,000 purchase · 2 units × $1,600/month = $3,200/month rent.
Annual costs: $4,200 taxes, $1,800 insurance, $1,200 utilities, $0 other. Management is 8%, repairs 5% and CapEx 5% of effective gross income.
Annual gross rent
$38,400
Vacancy deduction
$1,920
Effective gross income
$36,480
Expenses including CapEx
$13,766
NOI after modeled reserves
$22,714
Loan amount
$262,500
Monthly loan payment
$1,746
Annual debt service
$20,957
Monthly cash flow before tax
$146
Cash required
$98,000
Cap rate / cash-on-cash
6.49% / 1.79%
DSCR
1.08×
At 10% vacancy: monthly cash flow falls to $15 and DSCR to 1.01×, with all other inputs unchanged.
Eight units: quick estimate
$1,000,000 purchase · 8 units × $1,400/month = $11,200/month rent.
Quick Estimate expenses: 40% of effective gross income, including a modeled CapEx reserve. Itemized inputs are not used in this mode.
Annual gross rent
$134,400
Vacancy deduction
$6,720
Effective gross income
$127,680
Expenses including CapEx
$51,072
NOI after modeled reserves
$76,608
Loan amount
$750,000
Monthly loan payment
$4,990
Annual debt service
$59,877
Monthly cash flow before tax
$1,394
Cash required
$280,000
Cap rate / cash-on-cash
7.66% / 5.98%
DSCR
1.28×
At 10% vacancy: monthly cash flow falls to $1,058 and DSCR to 1.21×, with all other inputs unchanged.
Dollars are rounded for display; ratios use unrounded values. The examples have different prices, rents and expenses, so their returns do not isolate the effect of unit count.
How much will a lender lend on a multifamily building?
Short answer: the smallest of the lender's limits. A multifamily lender works out the loan allowed by its maximum loan-to-value, the loan whose payment still leaves its minimum debt service coverage ratio, and, for some lenders, the loan that meets a minimum debt yield. Whichever is lowest is the loan. The calculator's Summary tab now runs this test on your own NOI and rate.
LTV limit = value × maximum LTV. Fannie Mae's Small Mortgage Loans for 5+ unit properties allow up to 80% LTV on loans up to $9 million (Fannie Mae program page).
DSCR limit = the loan whose annual payment equals NOI ÷ minimum DSCR. The same program's minimum is 1.25×, with amortization up to 30 years.
Debt yield limit = NOI ÷ minimum debt yield. A rate-independent test some balance-sheet and CMBS lenders add; agency small-loan term sheets usually do not state one.
Worked example: the eight-unit building above
Hypothetical inputs: the eight-unit example's NOI of $76,608, a $1,000,000 price, a 7% rate with 30-year amortization, 80% maximum LTV, 1.25× minimum DSCR and, for illustration, an 8% debt yield floor. The rate and debt yield are assumptions, not a quote.
Three loan limits for the same building: the shortest bar sets the loan
Loan-to-value limit$800,000
Debt coverage (DSCR) limit (binds)$767,651
Debt yield limit$957,600
Loan limits for the eight-unit example
Test
How it is solved
Loan
LTV
$1,000,000 × 80%
$800,000
DSCR
$76,608 ÷ 1.25 = $61,286 a year, or $5,107 a month, supports at 7% over 30 years
$767,651
Debt yield
$76,608 ÷ 8%
$957,600
Reading: coverage, not value, limits this loan to about $767,651, 76.8% of the price. The buyer would need about $232,349 down instead of the 25% ($250,000) assumed in the example, before closing costs. Each percentage point of rate moves the DSCR limit; the LTV and debt yield limits do not move with rate.
Price that still earns your target return
The same example earns 5.98% cash-on-cash at $1,000,000. Holding rents, expenses and 25% down at 7% fixed, the highest price that still earns 8% is about $931,096. The Sensitivity tab's “Max Purchase Price” gauge shows this figure for your deal. An earlier version of that gauge scaled the asking price up when a deal missed the target; it was corrected on October 20, 2026 and now solves for the price directly.
Underwritten NOI is usually lower than the seller's
Vacancy: lenders typically apply at least 5% economic vacancy even when a building is full. Enter that in the calculator rather than 0%.
Management: a market management fee is charged even if the owner self-manages.
Reserves: a per-unit replacement reserve is deducted. This tool already counts its CapEx reserve inside NOI.
Taxes and insurance: taxes are re-estimated at the purchase price and insurance at a current quote, not the seller's history.
Rates and terms in October 2026
Freddie Mac's weekly survey put the average 30-year fixed home-loan rate at 7.40% for the week of October 15, 2026 (PMMS via FRED), and the 10-year Treasury yield was 5.15% on October 19 (FRED DGS10). Loans on 5+ unit buildings are priced as a spread over Treasury yields rather than at the home-loan average, usually carry 5-, 7- or 10-year terms with 25- or 30-year amortization and a balloon, and often have prepayment terms. Use the rate from a dated lender quote. Freddie Mac replaced its Small Balance Loan program with a Conventional Small product for $2 million to $10 million loans on April 15, 2026 (Freddie Mac announcement); its leverage and coverage terms are set in its guide and by each lender.
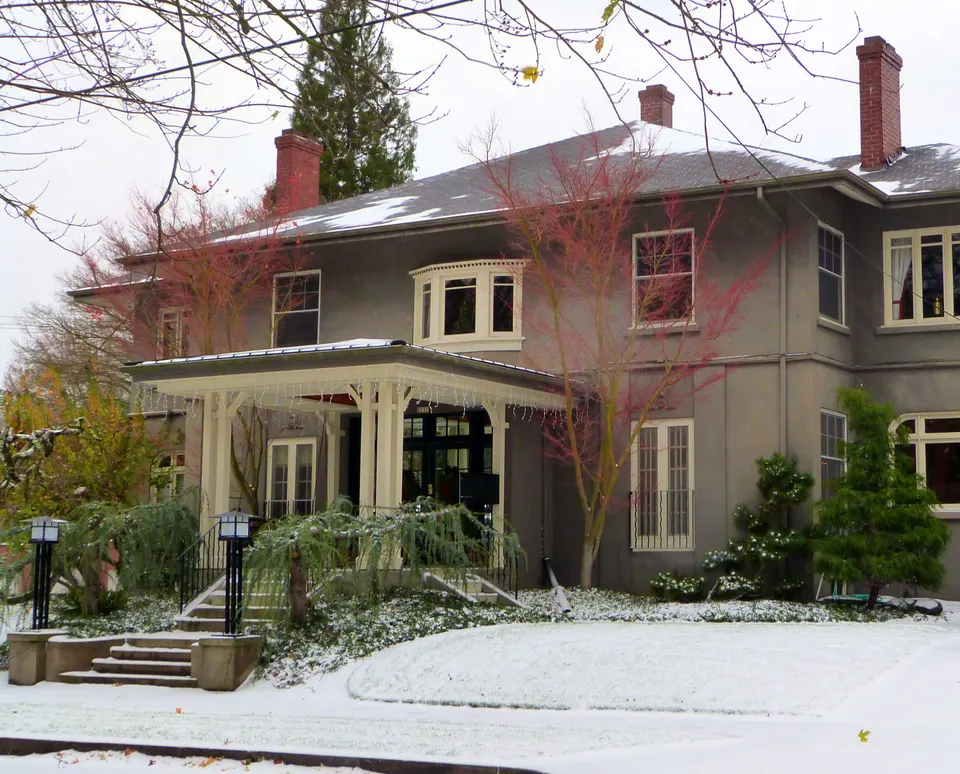
The H. R. Albee Fourplex (built 1917) in Portland, Oregon’s Irvington Historic District: a four-unit building of the kind this calculator models. Pictured for illustration; it is not one of the examples.
Read NOI, cap rate, DSCR and cash-on-cash together
NOI in this tool is effective gross income minus modeled operating expenses, including the CapEx reserve. Debt payments and income tax are excluded. Some lender and appraisal statements deduct reserves after NOI instead, so reconcile the reserve treatment before comparing their NOI or cap rate with these results.
Cap rate = NOI ÷ purchase price. It measures modeled income yield before financing, using this tool's after-reserve NOI.
Cash flow before tax = NOI − annual debt service. Divide by 12 for the monthly result. A positive NOI can still leave negative cash flow after debt.
DSCR = NOI ÷ annual debt service. A ratio of 1.00× means modeled income exactly covers debt service. Below 1.00×, it does not. With no debt service, the ratio is not applicable.
Cash-on-cash = annual cash flow ÷ cash required. In basic financing, cash required includes down payment, closing costs, loan points and initial rehab. It excludes appreciation, principal paydown and tax benefits from the return.
The result cards' targets are screening references, not loan approval rules. A lender may adjust income, reserves and debt service for its own test; see Fannie Mae's underwritten DSCR definition. Open Operating Statement to trace your income through expenses and debt payments.
How to calculate the value of a multifamily property
An income-based value estimate divides annual NOI by a comparable market cap rate expressed as a decimal. For illustration, $96,000 ÷ 0.065 is about $1,477,000. At 7%, the same income implies about $1,371,000. Use income and cap rates with the same reserve treatment, period and occupancy assumptions; do not mix an after-reserve figure with a before-reserve cap rate.
The main Cap Rate card works the other way: it divides your calculated NOI by the purchase price you enter. It is not an appraisal or an automatically selected market cap rate. Exit & Returns lets you explore sale assumptions separately. Gross rent multiplier (price ÷ annual gross rent) is another screening measure, but it ignores expenses and debt.
Multifamily mortgage assumptions and next checks
Use the down payment, rate and amortization from your lender's quote. The basic loan payment covers principal and interest; taxes, insurance and operating costs belong in expenses. Professional financing models are available in Pro for more complex structures.
Reconcile leases and collections with the trailing 12 months of income and expenses.
Verify post-purchase taxes, insurance quotes, owner-paid utilities and a building-specific replacement reserve.
Use Sensitivity to test lower rent, higher expenses and borrowing costs. Review exit cap rate and selling costs separately from first-year cash flow.
For buildings with retail or commercial space, read the mixed-use property analysis guide and check each lease's expense obligations before combining the income.
Frequently asked questions
Is the multifamily calculator free?
Yes. Unlimited property analysis without an account includes full results, charts, sensitivity testing, projections and recommendations. Create a free account to save a deal. Pro adds professional financing, partnership models, portfolio management, unlimited saved deals and report exports.
Can I use this for a duplex, triplex or fourplex?
Yes. The calculator supports 2–20 units, including duplexes, triplexes, fourplexes and small apartment buildings. It models the building as a rental investment. If you will live in a unit, the House Hack Calculator separates your housing cost from tenant income. The Single Family Rental Calculator offers residential loan options for 1–4 unit investments.
Do I enter rent per unit or for the whole building?
In Simple mode, Total Monthly Rent is the combined rent from all units. In Rent Roll mode, enter each unit separately. Occupied and notice units contribute current rent; vacant units contribute zero. The vacancy and credit loss percentages then reduce the remaining rent, so avoid counting the same vacancy twice.
Does NOI include the mortgage payment or CapEx reserves?
The calculator subtracts modeled operating expenses, including CapEx reserves, from effective gross income to calculate NOI. It subtracts debt service afterward to calculate cash flow before tax. Some lender or appraisal statements deduct reserves after NOI, so match definitions before comparing NOI, cap rate or DSCR.
How do you calculate the value of a multifamily property?
An income-based estimate divides annual NOI by a comparable market cap rate expressed as a decimal. For example, $96,000 divided by 0.065 is about $1,477,000. Use a consistent reserve and occupancy basis. The main calculator reports cap rate from your NOI and purchase price; it does not select a market cap rate or produce an appraisal.
What down payment and DSCR should I use?
Enter the down payment and financing terms from your lender’s quote. This tool calculates DSCR as modeled NOI divided by annual debt service; 1.00× means modeled income exactly covers debt payments. On-screen targets are screening references, not approval criteria. Requirements and income adjustments vary by lender, loan structure and property.
How much will a lender lend on a multifamily property?
Usually the smallest of three limits: value times the maximum loan-to-value, the loan whose annual payment equals NOI divided by the minimum DSCR, and, for some lenders, NOI divided by a minimum debt yield. In the eight-unit example on this page, an 80% LTV allows $800,000 but a 1.25× DSCR at 7% over 30 years allows about $767,650, so coverage sets the loan.
What is the minimum DSCR for a multifamily loan?
It depends on the lender and program. Fannie Mae’s Small Mortgage Loans for 5+ unit properties publish a 1.25× minimum DSCR and 80% maximum LTV for loans up to $9 million. Banks and DSCR lenders commonly use 1.20× to 1.25×. Lenders apply the ratio to their own underwritten NOI, which is often lower than the seller’s.
What interest rate should I use for a multifamily loan?
Use a dated quote. Loans on 5+ unit buildings are priced as a spread over Treasury yields and usually have 5- to 10-year terms. For context, Freddie Mac’s weekly home-loan average was 7.40% for the week of October 15, 2026, and the 10-year Treasury yield was 5.15% on October 19, 2026. The Sensitivity tab’s rate grid is centered on the rate you enter.