NOI does not include depreciation or mortgage payments. Net operating income measures what a rental earns after operating expenses, before financing and owner income tax. In this guide, capital reserves also sit below NOI.
That distinction changes how you read a listing. Our hypothetical house produces $17,072 of NOI, but only $3,597 of cash after its reserve and mortgage. A separate tax calculation produces another answer. None of those numbers can stand in for the others.
The NOI formula and the reserve convention
Effective income = scheduled rent + other property income - vacancy and collection loss
NOI before reserves = effective income - operating expenses
Two buyers using the same operating assumptions calculate the same NOI even if one pays cash and the other borrows. Their cash flow differs. Buyers can still arrive at different NOI figures when they use different rents, expenses, reporting periods or reserve conventions.
Fannie Mae's Analysis of Operations definitions, Form 4254.DEF dated August 2024, place capital expenditures/replacement reserves after NOI. That is a documented multifamily reporting convention, not a promise about every residential lender. RentalCalcs' single-family calculator includes its capital reserve in displayed NOI; the reconciliation below explains the difference.
Does NOI include depreciation?
No. Depreciation is excluded from property NOI. It belongs in a separate tax calculation. A depreciation deduction does not mean the owner paid that amount from this year's rent.
For tax purposes, IRS Publication 527 explains depreciation as recovery of a rental property's cost. The allowable amount depends on the property's basis, method and applicable timing. Our rental depreciation guide explains those inputs; do not substitute a purchase-price percentage for the tax records.
How it works · illustrated
Start with the operating ledger. Then take separate paths to the owner’s cash budget and tax records.
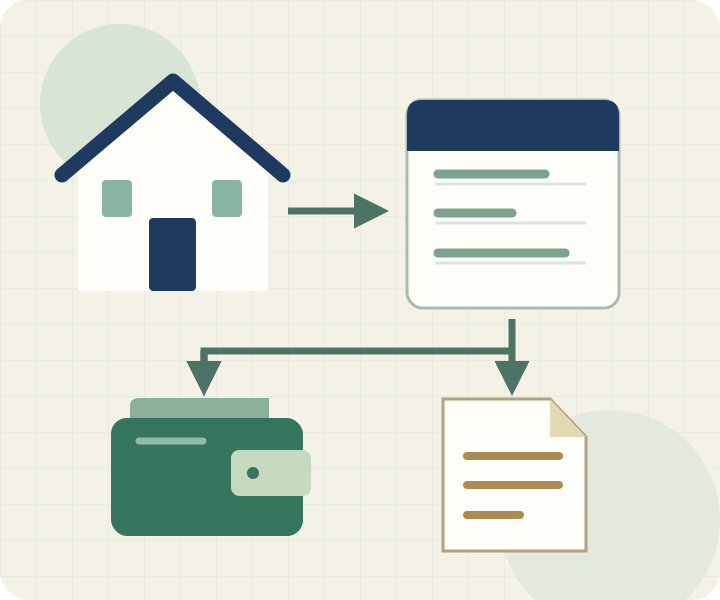
- Property operations
- NOI
What is left after the recurring costs of running the rental?
- Owner cash budget
- Cash available
What remains after the full loan payment and money set aside for future work?
- Rental tax calculation
- Tax result
What do actual income, deductible costs, interest and allowable depreciation produce?
The tax path is not the next step after cash flow. In particular, principal reduces cash but is not a rental expense deduction; depreciation is not a new cash payment.
Original RentalCalcs illustration. Conceptual artwork, not a monetary scale. Reviewed October 16, 2026. Tax distinction: IRS Publication 527.
NOI feeds the cap-rate calculation: annual NOI divided by price. Loan coverage may use underwritten income after reserves. The DSCR guide explains why you need the lender's numerator and debt definition before comparing a ratio with its requirement.
Income: rent, other income, and the vacancy deduction
The example is a one-unit house renting for $2,200 a month, with no other income. Scheduled annual rent is $26,400. A combined 5% vacancy and collection-loss allowance removes $1,320, leaving $25,080 of effective income. All property and financing inputs here are hypothetical.
This is a forecast. If you start with actual bank receipts that already exclude empty months and unpaid rent, do not deduct those losses again. Reconcile collections to the leases before adjusting a future year's budget.
Keep in-place lease rent separate from expected rent after a renewal or turnover. Parking and laundry income need collection evidence too. Refundable security deposits are not ordinary rental revenue when you expect to return them. The rent-roll verification guide shows which documents to compare.
Expenses that belong in NOI
Operating costs keep the rental running: property taxes, rental insurance, routine repairs, management, owner-paid utilities, association dues and relevant administrative or leasing costs. This investment classification does not decide an item's tax treatment.
Here, annual operating expenses total $8,008. The calculation is $25,080 effective income minus $8,008 expenses, leaving $17,072 NOI before reserves. For comparisons across buildings, calculate the operating expense ratio on the same income basis and explain differences in included services.
The six operating-cost assumptions
Preview: 3 of 7 rows
| Expense | Assumption | Annual dollars |
|---|---|---|
| Property taxes | Hypothetical bill | $2,400 |
| Insurance | Hypothetical premium | $1,300 |
| Management | 10% of effective income | $2,508 |
| Routine repairs | Annual allowance | $1,500 |
| Other operating costs | Lawn, pest and administration | $300 |
| Owner utilities and HOA | None in this illustration | $0 |
| Total operating expenses | Before capital reserves | $8,008 |
If you self-manage, show both actual cash spending and a budget that could pay a manager. The difference compensates you for work and responsibility. It is not evidence that the building earns more rent.
The seller's tax and insurance bills document past costs. Your bills may differ because of assessment rules, exemptions, policy terms or rental use. Record the reason for each adjustment; neither automatic reassessment at the purchase price nor an insurance percentage is a universal rule.
Expenses that never belong in NOI: debt, capex, depreciation
Does NOI include mortgage interest or property taxes?
Mortgage interest and principal stay outside NOI; property taxes belong inside it. Owner income tax is separate from property tax. If a mortgage payment includes tax and insurance escrow, separate those amounts so they are not counted again after operating expenses.
This guide also places capital replacements and reserves below NOI. Replacing a roof and patching a leak are different cash needs. A reserve is cash earmarked for future work, not proof that work occurred. A reporting form that includes reserves needs an explicit adjustment before comparison.
| Annual stage | Dollars | Meaning |
|---|---|---|
| NOI before capital reserve | $17,072 | Property operating income |
| Income after $1,500 reserve | $15,572 | Available for financing and owner cash |
| Cash after reserve and debt | $3,597 | After $11,975 principal and interest |
The loan is $150,000 at an illustrative 7%, amortized over 30 years. It is not a current offer. We use the unrounded payment, about $998 monthly. The CFPB's amortization explanation shows why the principal and interest portions change even when the combined payment stays fixed.
In RentalCalcs' single-family calculator, displayed NOI is $15,572 for these assumptions. Its itemized operating expenses include the $1,500 CapEx reserve. Add that reserve back to compare with this guide's $17,072 NOI. The cash-flow result already includes the reserve; do not deduct it twice.
The calculator also deducts expected turnover costs in its income calculation. Count that cost once when reconciling your pro forma. Our example has no separate turnover charge beyond the stated loss and repair allowances, so it is not a full budget for an immediate move-out.
Why NOI, cash flow and taxable rental income differ
For this comparison only, assume the forecast became an actual year: $25,080 was collected and all $8,008 of operating costs were paid and deductible. The $1,500 reserve remains unspent. This does not turn a forecast vacancy allowance into a tax deduction.
The first 12 loan payments contain about $10,452 of interest and $1,524 of principal. Assume the owner's records support $6,000 of allowable depreciation, determined separately. We are not deriving it from the purchase price or assuming a full year of building depreciation.
Under these assumptions, the rental tax result before limitations is $620: $17,072 minus unrounded interest minus $6,000. Publication 527's expense and depreciation guidance distinguishes deductible rental interest from principal and explains the separate cost-recovery deduction. Other adjustments and owner-level loss limitations are outside this example; $620 is not the owner's tax bill.
The worked comparison · USD per year
Three views of the same hypothetical rental. Every bar starts at zero on the same $0–$18,000 scale. These results are alternatives to compare, not amounts to add together.
NOI before reserves$17,072
$25,080 effective income − $8,008 operating expenses
Cash available before income tax$3,597
$17,072 NOI − $11,975 principal and interest − $1,500 reserve
Rental tax result before limitations$620
$17,072 operating result − $10,452 interest − $6,000 assumed allowable depreciation
Tax case assumptions: actual annual collections equal $25,080, all $8,008 of operating costs were paid and deductible, and allowable depreciation is assumed to be $6,000. The reserve is unspent. No personal use, extra fees or other adjustments are modeled. This is a rental result before owner-level limitations, not a tax bill.
Original RentalCalcs calculation, reviewed October 16, 2026. A $150,000 loan at an illustrative 7% over 360 monthly payments produces $10,452 interest and $1,524 principal in its first 12 payments. Figures use unrounded payments; rounded components can differ by $1. The $6,000 depreciation assumption is not calculated from the purchase price. This fixed comparison does not change when you edit the separate budget below.
Open the NOI reconciliation worksheetTest what operating changes do to cash
Try the downside below: rent falls 5% to $2,090, collection loss rises to 8%, taxes rise to $3,600 and insurance to $1,600. With other assumptions unchanged, NOI falls to $13,766 and cash after reserves and debt to $291 a year. Positive NOI alone leaves very little room for another expense.
The interactive budget changes operations and cash only. It does not calculate taxes or update the fixed comparison above. Its 5% loss is a combined vacancy and collection assumption; it is not an additional tax expense.
Try the worked example
Follow the same dollar through the budget
Hypothetical annual budget, reviewed October 3, 2026. Change four assumptions. This illustration is available without an account; it does not save a deal.
Annual cash after reserve and debt
$3,597
5.3% of $68,000 committed
NOI before capital reserve
$17,072
$15,572 after the $1,500 reserve.
Original RentalCalcs calculation from the inputs above. Bar lengths show dollar magnitude; a red bar is a deficit. Exact categories appear in the table below.
See all 9 budget lines
| Budget line | Annual dollars |
|---|---|
| Scheduled rent | $26,400 |
| Vacancy and collection loss | -$1,320 |
| Effective income | $25,080 |
| Operating expenses (no capital reserve) | -$8,008 |
| NOI before capital reserve | $17,072 |
| Capital reserve | -$1,500 |
| Income after capital reserve | $15,572 |
| Principal and interest | -$11,975 |
| Cash available after reserve and debt | $3,597 |
Fixed assumptions: $200,000 purchase; $150,000 loan at an illustrative 7% for 30 years; management 10% of effective income; repairs $1,500; other operating costs $300; capital reserve $1,500; initial cash $68,000. No other income, growth, income tax or sale proceeds. Debt uses the full amortizing payment; displayed dollars are rounded.
Download the budget and evidence worksheet (CSV)Three NOI errors that inflate a listing's numbers
Suppose a hypothetical listing counts all $26,400 of scheduled rent, omits management and budgets only $500 of repairs. Holding other costs constant produces a claimed NOI of $21,900. Correcting three assumptions removes $4,828, bringing NOI back to $17,072.
| Correction | Reduction to claimed NOI |
|---|---|
| Restore 5% vacancy and collection loss | $1,320 |
| Add 10% management on effective income | $2,508 |
| Raise repairs from $500 to $1,500 | $1,000 |
| Total difference | $4,828 |
A zero management line can accurately describe an owner's cash spending. A managed pro forma answers a different question. The mistake is presenting those two budgets as equivalent, not the mere existence of a zero line.
At an assumed 7% cap rate, the $4,828 difference translates to roughly $69,000 of implied value. That sensitivity calculation is $4,828 divided by 0.07, not an appraisal or a local cap-rate claim. It explains why verifying an annual expense matters to the purchase-price argument.
Use matching periods, too. A year's income cannot be compared with six months of debt service. Label trailing results, a future forecast and adjustments separately.
The St. Louis rental budget follows operating income through loan payments and reserves in a base case and a lower-rent case.
Rebuild the seller's NOI before you trust it
Use the NOI reconciliation worksheet to keep the seller's amount, your adjustment, its reason and the supporting record together. The CSV beneath the interactive budget preserves the example's operating lines.
- Match unit leases and the rent roll to collections. Distinguish current rent from future rent assumptions.
- Choose actual receipts or scheduled income with a loss allowance for the same period. Avoid deducting vacancy twice.
- Reconcile management, utilities, repairs and administration. Check whether the management fee covers leasing and renewals.
- Establish prospective taxes and insurance. Carry unresolved costs into the downside case.
- Separate acquisition work, routine repairs and the future replacement reserve.
- Show NOI before reserves, income after reserves and cash after debt. Keep the tax calculation and lender's convention separate.
Put verified inputs into the single-family calculator for a one-to-four-unit rental, or the multifamily calculator for five-plus units. Reconcile each tool's reserve treatment to the number you intend to compare.
Then ask whether the cash left justifies the money committed. The cash-on-cash return guide takes that next step. NOI alone cannot answer it.
Reviewed October 16, 2026 by RentalCalcs. Sources accessed on that date. Figures are original calculations from hypothetical inputs; tax references use IRS Publication 527 (2025). This is an operating-income explanation, not a property appraisal or individual tax return calculation.
Get new articles and market updates
Investing guides and market data, straight to your inbox. Unsubscribe anytime.
