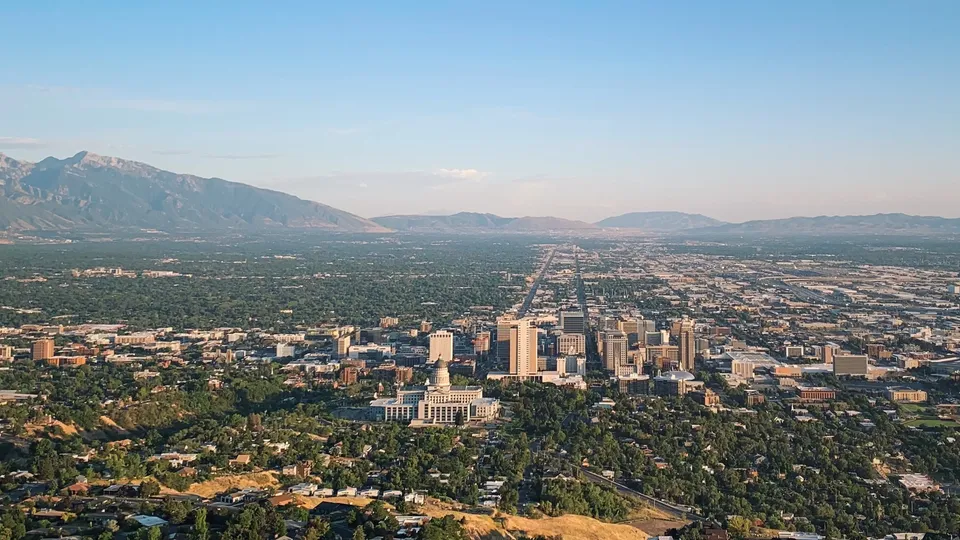

Utah cap evidence: what can actually be compared
Northmarq reports a 5.3%–6.2% cap range on the handful of Q2 2026 Wasatch Front deals with disclosed pricing. It is a selected transaction range, not a Utah average or a separate rate for every city. The buying decision is whether today’s collections support the price while nearby lease-ups are still competing for tenants.
“Southern submarkets leading the charge.”
Marcus & Millichap · Salt Lake City Q2 report. Marcus & Millichap’s Q2 report discussing earlier Q1 leasing; not current city cap rates.
A capitalization rate is annual net operating income divided by property price, before debt. A published cap metric helps select comparables; it cannot establish the subject property’s income or condition.
Dated evidence, not a statewide average
Original display. The numeric scale starts at zero and ends at 10%. Historical, asking and transaction observations retain their labels; missing data is not zero.
| Geography / asset | Period | Reported cap | Basis and limits |
|---|---|---|---|
| Wasatch Front disclosed-price transactions | Q2 2026 | 5.3%–6.2% | Selected sale-cap range. Only a handful of deals; cap denominator, weighting and NOI convention undisclosed. |
| Downtown, Provo/Orem, Ogden and Logan | October 2026 review | No separate cap verified | Coverage gap. Operating or transaction context does not establish city or neighborhood cap rates. |
The range spans 90 basis points but says nothing about the number of properties at either end. Underwrite an older small building against similar sales and a new leased-up community against stabilized institutional comparables. A midpoint would conceal those different buyer pools. Neither this range nor one year’s average is a promised exit yield.
One percentage point = 100 basis points. Multiple publishers sharing a dataset do not create independent confirmation. Asking caps, reported-sale medians, averages and modeled county indexes must remain distinct.
The local decisions behind the cap rate
| Market / measure | Period | Value | Boundary |
|---|---|---|---|
| Published market vacancy | Q2 2026 | 6.8%; −30 bps quarter / +10 bps year | Publisher market; not physical or economic vacancy at the subject. |
| Monthly asking rent | Q2 2026 | $1,608; +1.6% quarter / −0.4% year | Asking rent excludes a verified concession and collection bridge. |
| Units under construction | Q2 2026 | 12,758 | Pipeline is a stock, not a year’s deliveries. |
| Earlier southern-market signal | Q1 2026 | Provo and Orem-Lehi vacancy each fell 40 bps | Q1 observations in a Q2 report; a different submarket universe. |
Downtown Salt Lake City: underwrite the lease-up overlap
Observed evidence and boundary. Northmarq identifies Downtown as the vacancy outlier and a concentration of upcoming deliveries.
A new lease signed during a competing building’s promotion can overstate sustainable collections if the concession is omitted. The relevant comparison is the next renewal and turnover season, not a metro asking-rent headline.
Direction. Editorial base case: require demonstrated income stabilization before accepting a tighter exit yield. Separate the benefit of filling vacant units from any assumption that investors will pay more per dollar of NOI.
What would change the view. A shrinking future pipeline would not protect a building competing with units already finished. Faster concession-free renewals would weaken the cautious case.
Before underwriting. Obtain a unit-level concession ledger, signed renewal offers and the opening dates of directly competing projects. Model the leasing shortfall as cash required before stabilization.
Evidence: Northmarq · Wasatch Front Q2 2026, pp. 1–4. Retrieved October 19, 2026. Interpretations and property decisions are RentalCalcs analysis.
South Jordan/Riverton and Provo/Orem: test the boundary of recovery
Observed evidence and boundary. Northmarq highlights southern improvement; Marcus & Millichap’s earlier-quarter commentary also identifies Provo and Orem-Lehi vacancy compression.
These are two brokerage perspectives, not matched samples. A favorable broad direction does not establish identical supply exposure for every project in the corridor. A property’s competing floor plans and school/work travel patterns matter more than a city label.
Direction. Editorial interpretation: stabilization is more defensible where renewals hold without new inducements. Treat a lower future cap as an additional upside, rather than the source of the deal’s required return.
What would change the view. New projects can move the competition across a submarket boundary. The earlier report’s construction estimate cannot be used as a current pipeline count.
Before underwriting. Map competing properties by bedroom mix and commute, document move-in incentives, and compare achieved renewal rent with the seller’s proposed rent. Keep student leases separate from conventional annual leases.
Evidence: Northmarq · Wasatch Front Q2 2026, pp. 1–4 · Marcus & Millichap · Salt Lake City Q2 report. Retrieved October 19, 2026. Interpretations and property decisions are RentalCalcs analysis.

Ogden, Logan and older private-buyer stock
Observed evidence and boundary. Northmarq describes small older-property trades across secondary Wasatch Front markets. No separate local cap is supplied.
A small-property buyer may face concentrated vacancy, self-management assumptions and a large repair bill relative to NOI. Institutional price-per-unit movement is a poor shortcut for this stock.
Direction. Editorial interpretation: use recurring maintenance and professional management in the base NOI even if the seller performs the work. A larger quoted yield can disappear after those substitutions.
What would change the view. An inspected, recently renewed building with transferable maintenance records may need less near-term cash. Age alone does not establish condition or a required premium.
Before underwriting. Reconcile roof, sewer, heating and electrical work with inspection findings and invoices. Request actual comparable closing income before assigning an Ogden or Logan exit cap.
Evidence: Northmarq · Wasatch Front Q2 2026, pp. 1–4. Retrieved October 19, 2026. Interpretations and property decisions are RentalCalcs analysis.
The residential exemption is an underwriting document
Observed evidence and boundary. Utah’s Tax Commission describes a 45% primary residential exemption and qualification for eligible tenant-occupied residences. Its current page flags new application requirements beginning January 2027.
A sale and a change in tenancy can create a documentation task precisely when the buyer is also funding repairs and leasing. Assuming the seller’s tax bill carries forward hides that exposure.
Direction. Editorial interpretation: use a written assessor-based buyer tax estimate and confirm filing obligations before committing the cash budget. Do not treat the exemption percentage as a tax rate.
What would change the view. The property’s actual use, land allocation or eligibility may differ. A general state explanation does not decide a mixed-use parcel.
Before underwriting. Obtain the assessment card, eligibility/declaration record, applicable local levy and a dated explanation of post-transfer filing requirements from the county.
Evidence: Utah State Tax Commission · primary residential exemption. Retrieved October 19, 2026. Interpretations and property decisions are RentalCalcs analysis.
Secondary markets and missing evidence
| Market | Coverage | Remaining gap |
|---|---|---|
| Salt Lake / Davis / Weber / Utah counties | Dated Wasatch Front report and selected sales; local operating commentary. | No current cap table for every county, city, class or neighborhood. |
| Southern Utah, St. George, Cedar City and resort markets | Not priced by this edition. | Obtain local closed-sale income, seasonality, tenant mix, insurance and liquidity evidence; do not export the Wasatch Front range. |
No neighborhood cap is assigned without matching neighborhood evidence. Missing evidence is a reason to obtain more comparables, not to add an arbitrary geographic spread.
Three cap-rate paths, and the evidence each needs
Observed: near-term leasing improved while the published annual asking-rent change remained negative. A quarterly rebound and an unfinished supply adjustment can coexist. This is a reason to examine collections, not to label every Utah market recovered.
Publisher outlook: Northmarq expects remaining deliveries to keep vacancy elevated before the pipeline thins. Marcus & Millichap’s Q2 public commentary concerns earlier Q1 southern-market improvement. They use different geographies and periods; agreement about direction is not independent confirmation of a cap statistic.
RentalCalcs interpretation: the base underwriting case is income stabilization with a conservative resale yield. A successful purchase should survive without marketwide compression. The dated sale range helps frame questions, while financing quotes and the subject’s collected NOI determine the offer.
Compression: stabilized income attracts a broader buyer pool
Fewer directly competing openings and sustained collections could let buyers accept less income yield for a stabilized building.
Watch: Concession-free renewals, completed lease-ups, comparable sale income and live loan quotes.
Invalidated or weakened by: Rising concessions or debt costs despite stronger physical occupancy.
Underwriting consequence: Keep any tighter exit cap as upside until the property demonstrates collections.
Stabilization: occupancy improves, required yields hold
Rent-roll gains may offset buyer costs while financing and repair uncertainty hold pricing discipline.
Watch: Economic occupancy, buyer tax estimate and cash after replacement reserve.
Invalidated or weakened by: Persistent collection misses or clear matched-sale repricing.
Underwriting consequence: Bid from current sustainable NOI; retain a wider-cap stress.
Expansion: remaining lease-ups meet expensive debt
Competing promotions can lower collected income just as buyers demand more yield to carry financing and capital work.
Watch: Turnover downtime, concessions, lender proceeds and required repair escrows.
Invalidated or weakened by: Durable renewals and multiple comparable closings at firmer pricing.
Underwriting consequence: Reduce price or leverage; separately fund the stabilization deficit.
These are conditional RentalCalcs scenarios, not publisher probability forecasts or basis-point targets. Policy rates, Treasury yields, lender spreads and the borrowing constant are different inputs. No policy-rate cut is assumed to pass through automatically to property debt.
What a wider cap does to your property value
Value = annual NOI ÷ (cap rate ÷ 100). At constant income, a higher cap reduces value. A move from 5% to 6% is +100 bps and a 16.7% value decline, not a 1% decline.
From this market evidence to an offer
- Separate the leasing deficitBuild a monthly cash calendar through competing project openings; identify which concessions reduce current collections and which renewals support the next-year NOI.
- Replace the seller’s cost basisInsert buyer taxes, bound insurance terms, professional management and actual repair contracts. Keep initial work and replacement reserve outside cap NOI.
- Price two independent risksStress lower collected NOI and a wider exit cap together. Keep financing and stabilization cash in the acquisition budget rather than hiding them inside the cap rate.
Hypothetical assumptions. NOI change is cumulative over your chosen holding period, not an annual growth rate. Results exclude debt, sale costs, taxes and interim cash flow.
Starting value $3,200,000
Exit value $3,285,333 (+2.7%)
$224,000 starting NOI at 7% → $246,400 exit NOI at 7.5%. NOI must change by 7.1% to preserve starting value at this exit cap rate.
Fixed reference matrix: your income has to offset the multiple
| Total NOI change | 6.50% exit | 7.00% exit | 7.50% exit | 8.00% exit |
|---|---|---|---|---|
| -10% total NOI | -3.1% | -10.0% | -16.0% | -21.2% |
| 0% total NOI | +7.7% | 0.0% | -6.7% | -12.5% |
| +10% total NOI | +18.5% | +10.0% | +2.7% | -3.7% |
| +20% total NOI | +29.2% | +20.0% | +12.0% | +5.0% |
This fixed matrix does not change when you edit the interactive tool. No selling costs, tax, debt payoff or interim cash flows are included. Total NOI growth is cumulative, not annual. Use a full cash-flow model for an investment return.
A buyer budget that reconciles before the debt
Hypothetical 20-unit acquisition at $3,200,000, with $1,600 scheduled monthly rent per unit. These assumptions illustrate a process; they are not market rents, quoted insurance or a forecast for any property.
Hypothetical conventional apartment acquisition, not a Wasatch Front sale. Test extra concessions, buyer exemption eligibility and a separate catastrophe cash allowance.
| Budget line | Annual amount |
|---|---|
| Scheduled apartment rent | $384,000 |
| Other recurring income | $6,000 |
| Vacancy / concessions / collection loss | −$30,000 |
| Effective gross income | $360,000 |
| Buyer property taxes | −$40,000 |
| Insurance allowance | −$18,000 |
| Owner-paid utilities | −$18,000 |
| Recurring maintenance | −$28,000 |
| Management | −$22,000 |
| Administration / licenses / other recurring | −$10,000 |
| NOI before financing and reserves | $224,000 |
Going-in cap: 7.00%. Immediate work of $120,000 is capital spending outside NOI; recurring repairs are already included above. An annual $10,000 replacement reserve is deducted below NOI in this example.
| Measure | Result / assumption |
|---|---|
| Loan / interest / amortization | $1,920,000 / 6.5% assumed / 30 years; monthly amortizing payments, no interest-only period |
| Annual principal and interest | $145,628 |
| Replacement reserve outside NOI | $10,000 |
| Cash flow after debt and reserves | $68,372 |
| Down payment + closing + initial work | $1,280,000 + $64,000 + $120,000 = $1,464,000 |
| Cash-on-cash, before income tax | 4.67% = cash flow ÷ total invested cash |
| DSCR, before / after replacement reserve | 1.54× / 1.47× |
| Debt yield, before / after replacement reserve | 11.67% / 11.15% |
The interest assumption is not a current loan quote. DSCR = the stated NOI numerator ÷ annual debt service; debt yield = the stated numerator ÷ loan principal. Lenders may deduct reserves or make other adjustments. Closing and initial work are funded from cash; no extra initial reserve deposit is assumed. If a lender requires one, add it to invested cash. Yield on cost requires a separately defined stabilized NOI and total project basis; it is not the going-in cap.
How much room does this buyer actually have? The amortizing loan constant is 7.58%: annual debt service divided by loan principal. Compare that payment burden with the 7.00% going-in cap, rather than comparing the cap only with the interest coupon. In this example, adding leverage reduces current equity cash yield before tax.
With debt service and reserves fixed, an annual NOI reduction of $68,372 (30.5%) would consume the remaining cash flow. This is an NOI stress, not the same percentage decline in rent; rebuild income and expenses separately.
Confirm buyer taxes and exemption paperwork
Use the county’s parcel-specific buyer estimate; verify the current declaration and January 2027 application change. Do not apply a blanket residential discount to every dollar of a mixed-use acquisition.
Evidence: Utah State Tax Commission · primary residential exemption. Retrieved October 19, 2026. Interpretations and property decisions are RentalCalcs analysis.
Quote seismic and flood coverage for the actual building
Utah’s insurance regulator explains that catastrophe coverage may require separate arrangements. Its consumer examples are not a commercial-apartment binder. Ask a licensed broker for exclusions, earthquake deductibles, ordinance coverage, business income and lender requirements.
Evidence: Utah Insurance Department · disaster preparedness. Retrieved October 19, 2026. Interpretations and property decisions are RentalCalcs analysis.
Match leases and property condition to the sale cohort
A disclosed-price trade does not audit the subject’s income. Separate conventional, student and short-stay revenue; use professional management and an inspected capital schedule.
Evidence: Northmarq · Wasatch Front Q2 2026, pp. 1–4. Retrieved October 19, 2026. Interpretations and property decisions are RentalCalcs analysis.

Free worksheet: turn unknowns into document requests
The printable worksheet gives you room to record the source, date and buyer adjustment for every income, expense, capital and exit assumption. It includes this edition’s local checks.
For a full property model, use the multifamily calculator. The single-family calculator supports a separate 1–4-unit workflow. These links do not transfer this page’s inputs; re-enter and verify your assumptions.
Compare local screening context: Salt Lake County. County rent-to-price screens are modeled indexes, not matched closed-sale NOI caps. Explore the Utah market directory.
Questions before an offer
Is the Wasatch Front range a statewide Utah cap rate?
No. It describes a limited disclosed transaction cohort. It does not price Southern Utah, a resort rental, a student lease or every small building in Ogden.
Does improving occupancy justify lower underwriting reserves?
No. Lease-up cash, replacement reserve and catastrophe deductibles solve different problems. Use inspection and policy documents to size them.
Why can a good quarterly rent result coexist with a cautious outlook?
Quarterly asking-rent gains may reverse part of an earlier decline. Collected rent can still lag, and completed competing units may take time to lease.
Source ledger, dates and refresh rules
Research retrieved October 19, 2026. Observations, publisher outlooks and our conditional interpretation are labeled separately. This ledger summarizes publicly available research; it does not redistribute proprietary report datasets. Brokers may be selling services or properties; appraisal commentary is not a guarantee of future pricing.
Northmarq · Wasatch Front Q2 2026, pp. 1–4
Geography: Publisher Salt Lake City / Wasatch Front market. Period: Q2 / H1 2026. Published: 2026-07-30. Accessed: 2026-10-19.
Property scope: Multifamily apartments. Class: As identified in observation; otherwise undisclosed. Substantive review: 2026-10-19.
Provider: Northmarq; operating series CoStar / Yardi; sales CoStar / Real Capital Analytics; see page-specific credits. Measure: Selected cap range, operating and transaction context. Statistic: Publisher-reported observation.
NOI convention: Not disclosed; do not assume trailing or forward NOI. Sample: Public report; metric-specific cap count not disclosed unless stated. Weighting: Not disclosed; do not combine publisher universes.
Limits: Cap count and NOI basis undisclosed; county/city boundaries differ across metrics. Refresh: Next quarterly edition, source correction or material rule change.
Marcus & Millichap · Salt Lake City Q2 report
Geography: Publisher Salt Lake City / southern submarkets. Period: Q1 observations / Q2 2026 commentary. Published: Not stated on public teaser. Accessed: 2026-10-19.
Property scope: Multifamily apartments. Class: As identified in observation; otherwise undisclosed. Substantive review: 2026-10-19.
Provider: Marcus & Millichap public commentary; teaser does not disclose full metric methodology. Measure: Earlier southern leasing perspective. Statistic: Publisher-reported observation.
NOI convention: Not disclosed; do not assume trailing or forward NOI. Sample: Public report; metric-specific cap count not disclosed unless stated. Weighting: Not disclosed; do not combine publisher universes.
Limits: Different period and nine-submarket universe; full report requires access; no gated content used. Refresh: Next quarterly edition, source correction or material rule change.
Utah State Tax Commission · primary residential exemption
Geography: Utah; county administration. Period: Current guidance; January 2027 transition. Published: Not stated. Accessed: 2026-10-19.
Property scope: Property guidance; not a cap observation. Class: Not applicable. Substantive review: 2026-10-19.
Provider: Utah State Tax Commission. Measure: Qualification and transfer documentation. Statistic: Official guidance.
NOI convention: Not applicable. Sample: Not applicable; official guidance, not market sampling. Weighting: Not applicable.
Limits: Parcel-specific advice and local levies still required. Refresh: Material rule change, revised guidance or parcel-specific confirmation.
Utah Insurance Department · disaster preparedness
Geography: Utah. Period: Current guidance. Published: Not stated. Accessed: 2026-10-19.
Property scope: Property guidance; not a cap observation. Class: Not applicable. Substantive review: 2026-10-19.
Provider: Utah Insurance Department. Measure: Flood and earthquake coverage questions. Statistic: Official guidance.
NOI convention: Not applicable. Sample: Not applicable; official guidance, not market sampling. Weighting: Not applicable.
Limits: Primarily consumer guidance; not a commercial quote or a property hazard assessment. Refresh: Material rule change, revised guidance or parcel-specific confirmation.
Refresh the affected figures and interpretation together when a new edition, correction or material operating rule appears. A retrieval or rebuild is not a new observation. Report a correction through RentalCalcs contact, including the source, edition, geography and affected claim.