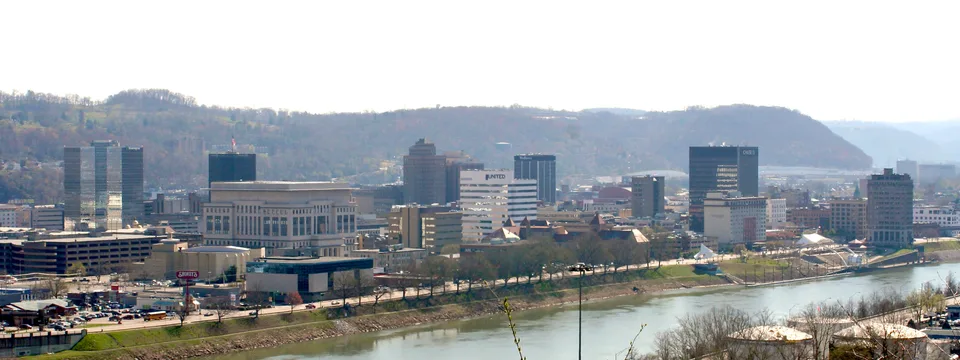

West Virginia cap-rate evidence by market
Capitalization rate is annual net operating income divided by price, before financing. A useful comparison requires matching the geography, property type, condition and income convention. These dated references are a starting point for that work.
Underwriting takeaway: Thin transaction evidence makes the income convention, repair scope and exit buyer more important, not less. Tight surveyed rental occupancy can coexist with an aging property that needs cash, limited comparable sales and a long sale process.
Dated cap references: points and stated ranges
| Geography / period | Reported cap | Supported comparison | Coverage boundary |
|---|---|---|---|
| Huntington — one historical six-unit apartment Closed March 15, 2025 | 12.73% reported transaction cap | One $210,000 sale of a 1930 building, reported fully occupied. | CoStar data unverified by publisher; NOI basis and conditions unstated. Not current metro pricing or a representative sample. |
| West Virginia latest reviewed mixed-commercial report Q4 2025 | No apartment observation in the four reported transactions | Mixed office, industrial and other commercial cap average excluded. | Its quarter-to-quarter movement cannot describe apartment compression or expansion. |
| Charleston, Morgantown, Eastern Panhandle and rural markets Review October 2026 | No current matched apartment cap series verified | Rental needs and occupancy evidence is not transaction pricing. | No statewide sample, geographic weighting or neighborhood rate can be inferred. |
One percentage point equals 100 basis points. No statewide weighted average is calculated. Total sales counts, where reported, are not cap-reporting sample counts. A change in the properties sold is not a repeat-sale valuation change.
Local facts become property decisions
| Market / period | Vacancy | Monthly rent | Rent change | Boundary |
|---|---|---|---|---|
| Advantage Valley surveyed multifamily — regional, not statewide April–June 2026 telephone survey | 98.4% overall occupancy; 96.6% pure market-rate | No comparable current asking-rent level used here | 2023–2026 two-bedroom median market rent +32.3% cumulatively | 161 projects / 11,384 units across ten counties; pure market-rate summary 58 projects / 5,072 units. Physical ready-unit vacancy, not economic vacancy. Three-year rent change is not annual. |
| Kanawha / Cabell / Putnam market-rate survey April–June 2026 | 0.5% / 0.6% / 14.7% vacancy | No asking-rent level imported | Putnam vacancy concentrated in one new project | County table includes market-rate units in mixed-program projects; different denominator from pure market-rate summary. No county cap inferred. |
| Historical Huntington six-unit sale March 2025 | Reported fully occupied | Not disclosed | Not disclosed | No economic occupancy or condition audit; cannot compare directly with regional survey occupancy. |
Charleston–Huntington region: housing need does not guarantee financeable rent
Observed: Bowen’s April–June telephone survey covered 161 properties and 11,384 units in ten counties, including affordable and market-rate programs. Pure market-rate projects were 96.6% occupied, versus 98.4% across all programs. The study counts ready-unit physical vacancies, not all economic vacancy. Its five-year housing-gap estimate includes both rental and for-sale housing. The release ties demand expectations to planned and ongoing investment, not completed and occupied apartments. Read the dated source.
Local mechanism: A shortage at an affordable rent does not prove enough households can pay the rent needed to cover a particular rehabilitation budget. The relevant question is the overlap between household income, acceptable unit condition, location and the subject’s proposed price. A regional gap also spans more geography and product than a single building’s renter catchment.
RentalCalcs interpretation: The study supports investigating durable demand for usable units, not capitalizing every projected job into current NOI. Keep existing leases separate from rent achievable after work and from a forecast gap. A compression case needs funded property trades as well as leasing strength.
What would change the view: Verified employer hiring, sustained net collections and multiple sale bids would strengthen the case. Delayed investment, affordability limits or repair costs above achievable rent support would weaken it, even if the region continues to need housing.
Property decision: Document who can afford the proposed rent, compare actual available units in the relevant commute area, and price code-compliant repairs. Ask whether the buyer can carry vacant work units without relying on a future job announcement.
Putnam County: one lease-up can dominate a small market’s vacancy
Observed: The study’s county table shows 14.7% market-rate vacancy in Putnam, versus 0.5% in Kanawha and 0.6% in Cabell. It attributes most Putnam vacancies to a single project opened in March 2026. These are county survey observations, not municipal cap rates. Read the dated source.
Local mechanism: When inventory is small, one opening can raise vacancy sharply even with active leasing. Stabilized older properties and a new lease-up have different risk and income. The county table includes market-rate units within mixed-program projects, so its count differs from the pure market-rate summary.
RentalCalcs interpretation: This is a concrete reason to examine the source inventory before calling a county weak or assuming the entire region is fully occupied. Putnam’s lease-up could absorb without a permanent rent reset, but a buyer must verify its actual current pace and concessions.
What would change the view: Slower leasing or discounts reaching older competitors would weaken the stabilization interpretation. Strong sustained collections and verified absorption without renewed concessions would strengthen it.
Property decision: Identify whether the subject directly competes with the new project, match unit mix and full effective rents, and budget concessions through the subject’s renewal dates. Do not apply either the regional occupancy or Putnam’s aggregate vacancy mechanically to every building.
Huntington: inspect what the historical double-digit cap leaves out
Observed: Vandalia’s Q1 2025 table identifies a fully occupied six-unit, 1930 apartment building at 2648 Fourth Avenue, sold for $210,000 with a reported 12.73% cap. The publisher explicitly says its CoStar data were not verified. The source gives no complete NOI reconciliation or capital-needs report. Read the dated source.
Local mechanism: Small older buildings can show a high annual income-to-price ratio and still require substantial cash per unit. One roof, utility system or long vacancy can materially change a six-unit owner’s cash flow. Full occupancy at closing does not establish rent collectability, legal unit count or the timing of major work.
RentalCalcs interpretation: Use this transaction as a warning to reconcile yield, not as evidence that every Huntington buyer should demand or receive the same cap. A lower purchase basis can be sensible when it compensates for real repair and liquidity risks; the reported cap alone cannot establish the compensation is sufficient.
What would change the view: Verified trailing income, legally usable units and a funded condition plan could make a high yield more credible. Deferred systems work, unrecorded expenses or non-market transaction terms would undermine the quoted return.
Property decision: Request the source NOI, leases, collections, tax classification, utility bills and inspection scope. Recompute cap before debt, cash after debt/reserves, and yield on price plus work. Keep this 2025 observation out of a claimed 2026 average.

Morgantown: do not use a therapy-office sale to price apartment leases
Observed: The latest reviewed Vandalia mixed-commercial quarter does not supply apartment evidence for Morgantown. The earlier Q1 table’s Morgantown transaction is a physical-therapy office, not rental housing. No current Morgantown apartment cap is established by either review. Read the dated source.
Local mechanism: Student-oriented and conventional apartments can have different lease calendars, guaranties and turnover burdens. If the subject depends on academic-year demand, a missed leasing season can mean a longer income gap than a conventional monthly vacancy assumption suggests. These are diligence questions, not a claim that every Morgantown apartment is student housing.
RentalCalcs interpretation: Keep Morgantown’s exit yield open pending apartment sale NOI and the actual lease model. An office lease-back or mixed-commercial average cannot resolve the missing comparable. Stability needs demonstrated renewals or preleasing and a buyer pool willing to finance that product.
What would change the view: Several current, closely matched apartment closings and seasoned preleasing would reduce uncertainty. A concentrated lease-expiration month, weak guaranties or a high turnover-work requirement would warrant more carry and a lower offer.
Property decision: Classify the income stream by unit or bed and lease duration, inspect signed lease and guaranty terms, and build a monthly cash calendar. Obtain local lender sizing for that exact property use rather than assuming conventional apartment terms.

Eastern Panhandle and rural acquisitions: price the actual local exit
Observed: Vandalia’s latest reviewed sample includes non-apartment transactions around the state, but it does not establish a Martinsburg or wider Eastern Panhandle apartment rate. Nor does the Charleston–Huntington housing study represent these markets or every rural county. Read the dated source.
Local mechanism: A property’s renter alternatives, employment access and local financing determine its income and resale options. A statewide average across other asset classes hides those differences. In a small acquisition, a single large repair or prolonged marketing period can be a material share of total invested cash.
RentalCalcs interpretation: Treat the absence of a cap sample as a reason to build a bottom-up bid, not a reason to manufacture a range. Require comparable net income and local financing, then test whether a slower exit remains affordable. A distant metro’s tighter cap should not be the residual that makes the deal work.
What would change the view: A broader local set of apartment closings and multiple funded bids would improve price discovery. Weak local collections, uncertain legal use or unquoted restoration costs would strengthen the downside case.
Property decision: Get two local sale-income reconciliations, an address-specific flood/coverage review, a repair scope and realistic marketing carry. Do not convert a county rent-to-home-value index into a lender-ready apartment cap.
Where the local evidence stops
| Market | Verified coverage | Missing evidence |
|---|---|---|
| Huntington — one historical six-unit apartment | Closed March 15, 2025: 12.73% reported transaction cap | CoStar data unverified by publisher; NOI basis and conditions unstated. Not current metro pricing or a representative sample. |
| West Virginia latest reviewed mixed-commercial report | Q4 2025: No apartment observation in the four reported transactions | Its quarter-to-quarter movement cannot describe apartment compression or expansion. |
| Charleston, Morgantown, Eastern Panhandle and rural markets | Review October 2026: No current matched apartment cap series verified | No statewide sample, geographic weighting or neighborhood rate can be inferred. |
| Other regions / neighborhood caps | Qualitative diligence only where no matching sale series is verified | Current apartment cap evidence remains missing for Charleston, Morgantown, Martinsburg/Eastern Panhandle and rural West Virginia. The single Huntington case is historical. The ten-county study is not statewide. Mixed-program occupancy, pure market-rate occupancy and county market-rate vacancy have different denominators. None is a subject collections audit. No missing cap is filled with a commercial average, asking yield or modeled index. |
Place the ten-county housing survey beside the subject county; the regional survey does not establish a local sale yield. Kanawha County market context. Its screening measures remain separate from apartment sale NOI.
County tools serve a different task: inspect the West Virginia county directory for geographic context and its stated methodology. A modeled rent-to-value index cannot corroborate an observed apartment NOI cap. A broker’s asking yield is not a closed-sale observation.
Compression, stabilization and expansion each need evidence
Source synthesis: The brokerage transaction perspective reveals sparse and mixed-asset price evidence. The Bowen/Advantage Valley housing-needs perspective describes tight surveyed rental availability and prospective demand. They answer different questions: a need for housing is not a sale yield or a guarantee of rents sufficient to fund work. Vandalia uses unverified CoStar reports; Bowen’s regional research is a separate operating/needs perspective, not independent confirmation of transaction caps. The study’s economic-development sponsorship and broker commercial context are disclosed.
Publisher forecasts: The Advantage Valley release projects a five-year rental housing gap of 10,604 units, within a larger all-housing gap, under its study assumptions. This is a needs forecast rather than committed construction, completed job creation or an apartment price forecast. RentalCalcs assigns no statewide cap direction or numerical target from that forecast.
These cases are conditional editorial underwriting tests. They have no assigned probability or unsourced basis-point target. Short-term policy rates do not determine a property’s borrowing cost; benchmark yields, lender spreads, amortization and fees all matter.
Compression
Usable units generate durable collections and a broader financed buyer pool values the lower uncertainty. Regional housing need may support leasing, but only executable apartment sales can demonstrate a yield change.
Watch: Affordability at achieved rent, funded repairs, employer hiring and matched apartment closings.
Invalidation: Rent gains that cannot be collected, delayed jobs or larger required capital work.
Underwrite: Keep tighter exit pricing as upside; verify the acquisition without it.
Stabilization
Leasing demand supports occupancy while local financing, recurring costs and a limited sale set keep required yields property-specific.
Watch: Renewals, actual receipts, repair invoices and lender reserve requirements.
Invalidation: Persistent economic vacancy or repeated matched funded trades at another yield.
Underwrite: Use a property-specific flat-yield reference and retain working capital for turnover and sale time.
Expansion
Condition, affordability or debt constraints require more compensation for the same income. Thin buyer depth can increase carry even where regional rental need remains high.
Watch: Failed debt sizing, contractor bids, delinquency and marketing duration for comparable apartments.
Invalidation: Competitive financed bids supported by verified recurring net income.
Underwrite: Stress lower NOI, wider exit and a longer sale period together. Do not confuse a historical high cap with guaranteed cash return.
How much NOI would offset a wider exit cap?
Value = annual NOI ÷ (cap rate ÷ 100). The acquisition below has $54,000 NOI and a 9.00% entry cap. A hypothetical 10% exit at unchanged income gives $540,000 gross value, a -10.0% change. Preserving the purchase price requires 11.1% cumulative NOI growth. A one-percentage-point cap increase is +100 bps, not a 1% value decline.
- Reject mixed-commercial averages as apartment evidenceIncome: reconcile rent roll, concessions and actual receipts.
- Reconcile collected rent and legally usable units after repairsNOI: deduct recurring buyer expenses before debt; separate capital work.
- Fund turnover, uncovered restoration and a slower local exitValue: compare consistent NOI, then test financing and exit cash.
Hypothetical assumptions. NOI change is cumulative over your chosen holding period, not an annual growth rate. Results exclude debt, sale costs, taxes and interim cash flow.
Starting value $600,000
Exit value $540,000 (-10.0%)
$54,000 starting NOI at 9% → $54,000 exit NOI at 10%. NOI must change by 11.1% to preserve starting value at this exit cap rate.
| Total NOI change | 8.00% exit | 9.00% exit | 10.00% exit | 11.00% exit |
|---|---|---|---|---|
| -10% | +1.2% | -10.0% | -19.0% | -26.4% |
| 0% | +12.5% | 0.0% | -10.0% | -18.2% |
| +10% | +23.8% | +10.0% | -1.0% | -10.0% |
| +20% | +35.0% | +20.0% | +8.0% | -1.8% |
The fixed matrix does not change with the tool. These are hypothetical assumptions, not market forecasts. Both exclude debt payoff, selling costs, taxes and interim cash flow. Negative values are signed independently of color.
A reconciled acquisition: cap rate is only one result
Illustrative 12-unit acquisition: $600,000 price and $900 monthly rent per unit. Every budget input is a hypothetical assumption, not a property quote or local average. This small-building example tests whether repairs, reserves and restoration cash consume the apparent high going-in yield. Its 9% assumption is not a measured market cap.
| Income or expense | Amount | Treatment |
|---|---|---|
| Scheduled income | $129,600 | 12 × $900 × 12 |
| Vacancy / collection loss | -$12,960 | 10% combined allowance; avoid double-counting concessions |
| Effective income | $116,640 | Before recurring expenses |
| Buyer property taxes | $6,000 | Verify Class III / IV, value and district levies |
| Insurance | $9,600 | Commercial quote and flood/lost-rent review |
| Management | $9,331 | 8% of effective income |
| Recurring repairs | $12,000 | Initial rehabilitation is separate |
| Owner utilities | $12,000 | Verify bills and legal recoveries |
| Contracts / administration | $13,709 | Itemize remaining recurring costs |
| Total recurring expenses | $62,640 | Sum of the recurring cost rows |
| Net operating income | $54,000 | Effective income minus recurring costs; before debt |
| Replacement reserve | $9,600 | Below NOI in this example |
| Annual debt service | $27,736 | $330,000 loan; assumed 6.9%; 25-year monthly amortization |
| Cash after debt and reserve | $16,664 | Before income tax and distributions |
Buyer cost checks: West Virginia law generally assesses property at 60% of true and actual value; 60% is not the tax rate. The Tax Division distinguishes owner-occupied Class II from other property outside municipalities (Class III) and inside them (Class IV). Confirm the investor’s classification, district levies and current value with the assessor; do not copy owner-occupied benefits.
For older buildings, obtain repair bids, legal-use confirmation, utilities and replacement-cost coverage. FEMA’s NFIP guidance says most ordinary business policies do not cover flood and its flood policies exclude business interruption. Confirm commercial apartment policy form, limits, exclusions and lost-rent protection separately; a building claim need not replace the income lost during restoration.
The 55.0% loan-to-price assumption is not a lender offer. Down payment $270,000 + closing costs $18,000 + initial work $100,000 = $388,000 invested cash. Going-in cap is 9.00%; DSCR is 1.95× before reserves, or 1.60× after them. Debt yield before reserves is 16.36%. Cash-on-cash is 4.29% before income tax. Confirm lender income and reserve conventions.
Initial capital work is separate from recurring repairs. NOI divided by price plus initial work gives 7.71% yield on cost, excluding closing costs. It is a different denominator from going-in cap.
Original buyer-cost stress: An additional $9,000 recurring annual cost reduces NOI to $45,000, cash after debt/reserves to $7,664, and gross value by $100,000 at the same 9.00% cap. Reclassifying recurring costs as capital work would conceal this loss.
Official buyer-cost references: WV Legislature — Assessment basis §11-3-1; WV Tax Division — Property tax classifications; FEMA / NFIP — Buying flood insurance. These establish checks, not a parcel bill or premium.
Build a property analysisThe linked calculator opens separately and does not receive these assumptions. Enter the property’s actual budget and verify its reserve conventions. A link click is not a completed calculation or saved deal.
Questions to settle before the offer
Is the latest Vandalia commercial average an apartment benchmark?
No. The reviewed Q4 2025 table has no apartment transactions. Its asset mix cannot describe current apartment pricing.
Is 12.73% the current Huntington cap?
No. It is one reported March 2025 six-unit transaction with an undisclosed income basis and unverified source data.
Does 98.4% regional occupancy prove the subject has low risk?
No. It combines rental programs in a regional survey. Pure market-rate occupancy was 96.6%; neither figure audits the subject’s collections, condition, legal use or affordability.
What turns a high cap into a usable offer?
Verified recurring NOI, funded capital work, buyer taxes/coverage, executable debt and enough cash for turnover and the actual local exit.
Open the free printable worksheet
Record every source period and NOI convention, collect the buyer documents, and carry both lower income and a wider exit through the decision. The worksheet is free and requires no account.
Source ledger, limitations and refresh
Accessed and researched October 18, 2026. Observation periods, publication timing and this substantive review are separate. Brokerage publishers have commercial interests. Shared providers are disclosed; multiple publishers using one dataset are not independent corroboration. Missing sample size, weighting and NOI conventions remain unknown.
- Vandalia Real Estate — Q1 2025 cap review
Period / publication: Q1 2025; Huntington sale March 15; file path May 2025, publication day unstated
Underlying provider: CoStar; explicitly not verified by Vandalia
Method / scope: One historical six-unit apartment case extracted from a mixed-asset review; no market average inferred. NOI basis unstated. NNN excluded and only reported prices included; broker/appraiser commercial context.
Refresh trigger: A newer matched apartment closing with verified income. - Vandalia — Q4 2025 review / latest-report directory
Period / publication: Q4 2025; file path February 2026; latest listed edition on October 18 review
Underlying provider: CoStar; unverified by publisher
Method / scope: Four non-apartment transactions. Mixed-commercial cap average excluded entirely from apartment benchmarks; no apartment trend inferred.
Refresh trigger: New directory edition, especially any apartment observations. - Bowen / Advantage Valley — 2026 full housing-needs assessment
Period / publication: 2026 assessment; release August 27 / page August 28; rent changes cumulative 2023–2026
Underlying provider: Bowen National Research; Advantage Valley; support from ARC, AB Contracting and Service Wire
Method / scope: Regional surveyed rental/needs evidence, not cap data or statewide census. Pages VI-9 and VI-17: telephone survey April–June, 161 properties / 11,384 units, ten counties. Pure market-rate summary differs from county table including market-rate units in mixed-program properties. Physical ready-unit vacancy excludes unavailable economic vacancies; survey not census. Five-year gap depends on study assumptions.
Refresh trigger: Study correction, new survey, employer timing or changed affordability evidence. - WV Legislature — Assessment basis §11-3-1
Period / publication: Statute accessed October 18, 2026
Underlying provider: West Virginia legislature
Method / scope: 60% assessment ratio, not a property-tax rate or parcel estimate.
Refresh trigger: Assessor value, adopted levies or statutory change. - WV Tax Division — Property tax classifications
Period / publication: Guidance accessed October 18, 2026
Underlying provider: West Virginia Tax Division
Method / scope: Classes II, III and IV depend on use and municipal location; verify subject classification.
Refresh trigger: Ownership/use/location or local assessment change. - FEMA / NFIP — Buying flood insurance
Period / publication: Current guidance accessed October 18, 2026
Underlying provider: FEMA National Flood Insurance Program
Method / scope: Coverage education including business-interruption exclusions; not a quote or assurance of suitable limits for a particular apartment building.
Refresh trigger: Flood determination, binding policy terms and renewal.
Summarized facts and original interpretation are provided instead of copying report graphics or proprietary datasets. Corrections: use RentalCalcs contact and identify the market, source edition and claim. Verify the property’s leases, expenses, condition, legal use and financeable sale comparisons before an offer.