Indianapolis rent & investment research · IN
Indianapolis metro rent report
Rebuild the Indianapolis expense sheet before paying for renovated rents; the seller’s NOI may not survive your ownership.
Zillow all-home metro asking-rent index · All bedroom counts · Seasonally adjusted
By RentalCalcs editorial · Reviewed
Live refresh status unavailable; showing the dated source snapshot shipped with this edition.
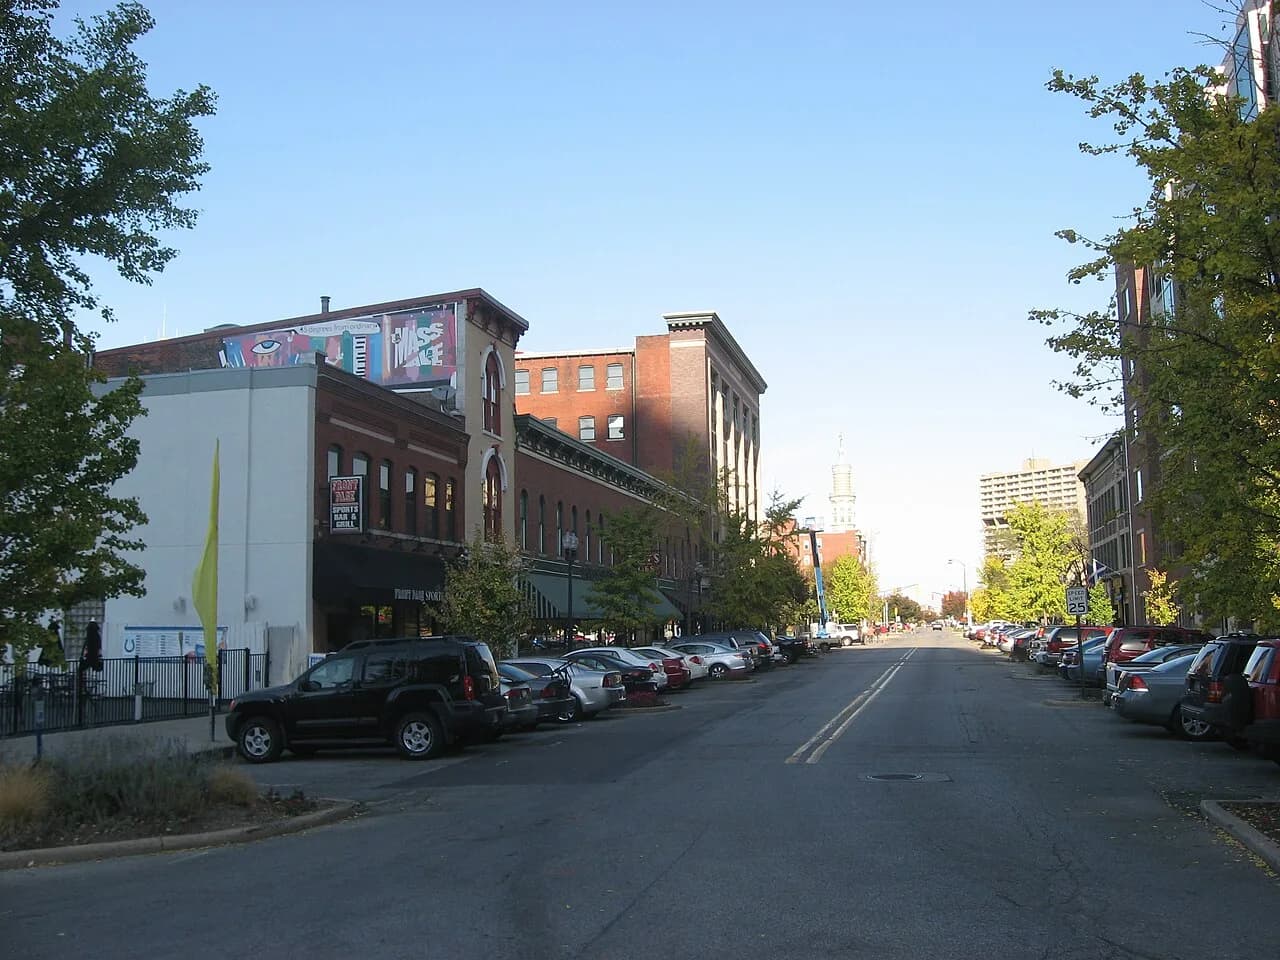

The investment view
Favor a rental with proven renewals, a parcel-specific tax estimate and a priced capital plan. Downtown renovation upside needs executed residential lease comparisons, especially while competing apartments are still absorbing recent supply. A $100 monthly increase across four units can be overwhelmed by recurring expense corrections. We would negotiate from the buyer’s operating budget before assigning value to cosmetic upside.
Indianapolis’s regional rent trend is stronger than the Q2 apartment pricing gain
The all-home provider-metro rent index is $1,528 monthly, +3.7% over one year and +12.3% over three years. An apartment renovation cannot automatically capture that broad change. Property type, bedroom mix, location, lease timing and concessions determine the actual comparison.
Monthly rent data
| Month | Typical rent |
|---|---|
| September 2021 | $1,190 |
| October 2021 | $1,204 |
| November 2021 | $1,217 |
| December 2021 | $1,224 |
| January 2022 | $1,230 |
| February 2022 | $1,238 |
| March 2022 | $1,250 |
| April 2022 | $1,266 |
| May 2022 | $1,277 |
| June 2022 | $1,291 |
| July 2022 | $1,301 |
| August 2022 | $1,309 |
| September 2022 | $1,309 |
| October 2022 | $1,309 |
| November 2022 | $1,312 |
| December 2022 | $1,320 |
| January 2023 | $1,328 |
| February 2023 | $1,333 |
| March 2023 | $1,340 |
| April 2023 | $1,343 |
| May 2023 | $1,349 |
| June 2023 | $1,349 |
| July 2023 | $1,350 |
| August 2023 | $1,353 |
| September 2023 | $1,360 |
| October 2023 | $1,368 |
| November 2023 | $1,375 |
| December 2023 | $1,379 |
| January 2024 | $1,384 |
| February 2024 | $1,391 |
| March 2024 | $1,396 |
| April 2024 | $1,401 |
| May 2024 | $1,405 |
| June 2024 | $1,409 |
| July 2024 | $1,416 |
| August 2024 | $1,421 |
| September 2024 | $1,427 |
| October 2024 | $1,428 |
| November 2024 | $1,431 |
| December 2024 | $1,437 |
| January 2025 | $1,446 |
| February 2025 | $1,453 |
| March 2025 | $1,457 |
| April 2025 | $1,462 |
| May 2025 | $1,467 |
| June 2025 | $1,470 |
| July 2025 | $1,471 |
| August 2025 | $1,471 |
| September 2025 | $1,473 |
| October 2025 | $1,479 |
| November 2025 | $1,483 |
| December 2025 | $1,486 |
| January 2026 | $1,486 |
| February 2026 | $1,486 |
| March 2026 | $1,490 |
| April 2026 | $1,495 |
| May 2026 | $1,499 |
| June 2026 | $1,506 |
| July 2026 | $1,513 |
| August 2026 | $1,522 |
| September 2026 | $1,528 |
MMG’s Q2 2026 apartment snapshot reported $1,323 average rent, only 0.2% annual growth and 91.1% occupancy. Over the trailing four quarters, 4,254 apartments were completed and 3,294 were absorbed. Those figures describe an earlier apartment population, not the all-home index or a current vacancy census. They support checking effective leasing terms before assigning a renovation premium.
A well-retained small building can outperform this apartment reading. Demonstrate that through receipts, renewals and the alternatives its residents actually consider. Conversely, a newly upgraded unit competing with amenity-rich apartments may need incentives even when its owner cites positive metro rent growth.
The Q3-labeled MMG pipeline, assembled August 19, names Versa at 6220 Guilford Avenue with 233 units and Mural Brownsburg with 164 units as pre-lease/lease-up projects. These dated entries identify competitors to investigate near a Broad Ripple or Brownsburg acquisition; their old forecast completion dates are not proof of current availability. Confirm whether they are still leasing, their current written incentives and which units actually compete with the subject.
A $6,000 annual expense correction beats a $100 monthly increase across four units
Hypothetical recurring annual NOI bridge
| Annual expense increase | NOI change after $4,464 extra collections |
|---|---|
| $3,000 | +$1,464 |
| $6,000 | −$1,536 |
| $9,000 | −$4,536 |
The offer should reconcile the seller’s trailing expenses with the buyer’s expected ownership. Request actual tax bills, the assessed-property card, an insurance quote for the planned rental use, utility bills and management scope. Separate an owner’s unpaid labor from a repeatable managed operation. A clean-looking seller statement is not enough if it omits recurring work.
Expense corrections can also run in the buyer’s favor. A documented utility separation or better insurance structure may improve cash flow. Count only savings supported by contracts, lawful billing and funded work; do not assume the cheapest quote or transfer a homestead benefit into an investment purchase.
Indiana’s 2% residential cap is not a promise to pay 2% of your purchase price
Indiana’s tax framework distinguishes homestead property from other residential property: the general caps are 1% and 2% of gross assessed value respectively. Local rates, classification, deductions and credits determine the computation, and voter-approved referendum taxes can sit outside the caps. A cap is not the same as an actual tax rate.
For a rental acquisition, identify the parcel’s assessed value, tax district and residential classification, then review which deductions or credits belong to the seller rather than the buyer’s intended use. Do not assume a purchase automatically resets assessed value to the sale price, or that the seller’s last payment represents the stabilized rental-owner bill. Mixed-use property needs additional classification review.
Build the property-specific estimate with the county and the state’s taxpayer tools, checking the assessment and payable year. Keep a range when the future bill is uncertain. A renovation that raises taxable value or a changed use can alter the business plan even if the rent premium is fully achieved.
For screening, compare Marion County, Hamilton County and Hendricks County research, then return to the actual parcel. A lower advertised purchase price in one county does not establish a lower expense-adjusted basis.
Mass Ave activity does not make a hotel or a suburban house an apartment comparable
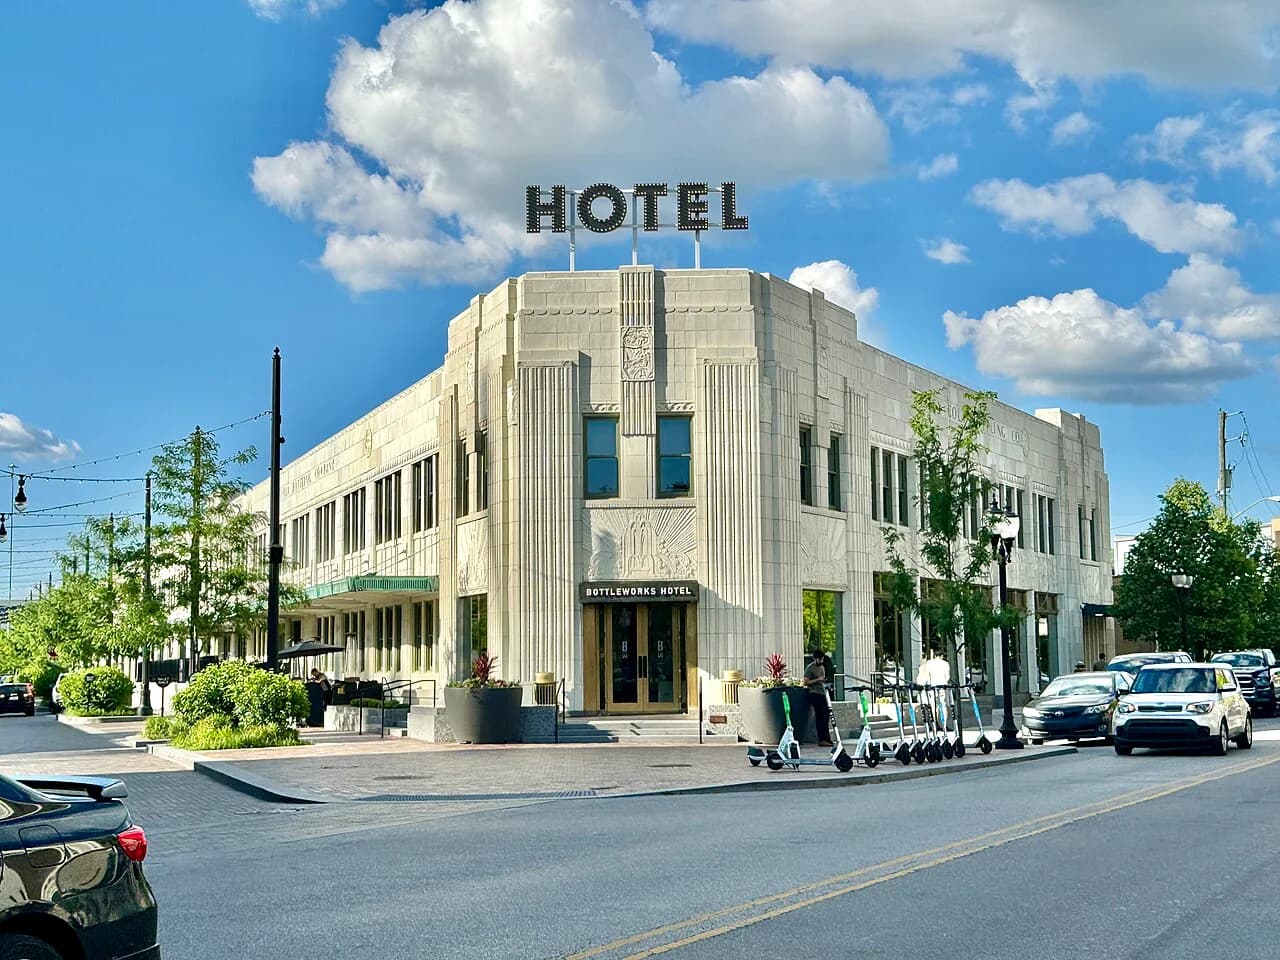

Massachusetts Avenue gives a buyer a plausible location story, but the photographed Bottleworks property is a hotel. Hotel room revenue includes services and a different stay pattern. Do not use a nightly rate or the district’s visitor activity to justify an unfurnished apartment’s annual rent.
For downtown or Mass Ave apartments, compare written effective rents, parking charges, utilities, recurring fees and concessions at alternatives with similar layouts. For a house in Carmel, Fishers or a Hendricks County location, compare other houses with similar space, parking and actual employment access. The relevant competitive set depends on the tenant’s alternatives, not whether two addresses share a metro.
For a mixed-use acquisition, isolate the shop’s rent, vacancy, improvements and share of common systems. Verify the residential legal-unit configuration and the city’s landlord registration requirements; Indianapolis notes an exception for excluded cities, so confirm the actual jurisdiction. A commercial lease does not validate the apartments upstairs.
The Indianapolis ZIP rent reference helps narrow the search. Use executed leases and condition-matched properties for the offer. The provider index also retains a different county boundary from the July 2023 official metro; the full crosswalk is available in the closed evidence panel.
Renovate only when the collected premium repays work, downtime and the new expense budget
Separate required systems from discretionary finishes. A roof, sewer repair or failed heating system may preserve legal occupancy and existing income; it does not necessarily produce a rent increase. Fund those obligations before treating a kitchen upgrade as the investment thesis.
For a cosmetic plan, document the premium in signed leases from comparable units and identify the likely vacant-turn period. Deduct incremental management, maintenance, utilities and recurring concessions from the premium. Compare the resulting annual cash benefit with the full project cost, including lost collections and carrying costs. A quick payback calculated from face rent alone can overstate the return.
Retaining a resident may outperform renovating immediately, particularly when competing apartments offer incentives. The strongest contrary case is a genuinely differentiated layout or house with repeatable demand and a low-cost upgrade. Evidence from that property can justify proceeding even when a broad apartment survey looks soft.
This $400,000 Indianapolis acquisition needs $47,000 beyond the price before operating reserves
Assume an occupied four-unit at $1,450 monthly per unit, 7% combined vacancy/collection loss, $29,000 annual operating expenses and $4,000 annual replacement reserves. A $35,000 initial repair budget plus $12,000 closing costs produces a $447,000 basis. Assumed financing is 65% of purchase price at 7% over 30 years. This is a hypothetical stabilized-year model, not an available building, loan quote or market cap-rate observation.
Acquisition lab · assumed Indianapolis property
Editable assumptions, not an available listing or financing quote. Closing costs are fixed at 3% of purchase price; repairs are paid upfront. No appreciation, tax benefits, refinancing proceeds or rent growth are needed to generate the results.
Edit property assumptions
| Measure | Base | Downside |
|---|---|---|
| Scheduled rent | $69,600 | $66,120 |
| After vacancy / collection loss | $64,728 | $59,508 |
| Net operating income (NOI) | $35,728 | $27,608 |
| Annual loan payments | $20,757 | $20,757 |
| Cash after debt + capital reserve | $10,971 | $2,851 |
| Debt coverage (NOI ÷ payments) | 1.72× | 1.33× |
NOI excludes financing and capital reserves. Operating expenses must include taxes, insurance, management, routine maintenance and owner-paid utilities. A reserve reduces spendable cash; it does not make a known roof or sewer replacement disappear. Results describe a stabilized year after initial repairs. Fund renovation downtime and carrying costs separately; they are not estimated here.
| Required yield | Base NOI | Downside NOI |
|---|---|---|
| 6.5% | $499,671 | $378,387 |
| 7.5% | $428,518 | $323,405 |
| 8.5% | $374,106 | $281,359 |
A price below a yield ceiling can still fail debt coverage or require more cash than you have. Check the loan terms, unit-level leases and a contractor’s scope before treating a modeled ceiling as an offer.
Replace the $29,000 expense allowance with a rental-owner tax budget, insurance, management, maintenance and owner-paid utilities before using the price ceilings. NOI excludes financing, reserves and initial repairs; spendable cash deducts debt and reserves. The combined downside reduces rent 5%, increases loss by three percentage points and raises expenses 10%. That tests whether leverage leaves enough room for an expense correction.
The $47,000 above purchase price does not include separate liquidity for construction downtime, acquisition carry or a prolonged empty unit. Do not allocate the same cash to repairs and operating reserves. If a price ceiling is attractive only before the tax or insurance quote arrives, it is an incomplete offer model.
Buy the corrected NOI; hold a productive lease and pass on an unfunded expense reset
| Plan | Proceed when | Reconsider when |
|---|---|---|
| Acquire an occupied rental | Receipts reconcile, ownership expenses are quoted and required capital is funded. | The seller’s NOI relies on owner-only tax benefits, free labor or missing utilities. |
| Hold and renew | The resident pays and the renewal beats vacant-turn economics. | Documented recurring premiums clearly exceed work, downtime and incremental costs. |
| Renovate near competing apartments | Matched signed leases support effective rent after incentives. | Face rents remain high while free months or vacancies persist. |
A newer comparable apartment survey showing firmer occupancy and effective rents would improve the renovation case. So would actual renewals at the subject demonstrating resilience. Neither signal removes the need for a buyer-specific expense budget. Use the rental-property calculator or multifamily calculator to extend the debt and capital schedule.
For renters, compare fees, utilities, parking and post-incentive rent alongside condition. A district’s attractions do not compensate for a lease whose full recurring cost exceeds the household budget.
Sources and methodology
Evidence behind this report
- MMG Indianapolis Q2 2026 public apartment snapshot: 91.1% occupancy, $1,323 average rent, 0.2% annual rent change, 4,254 trailing-four-quarter completions and 3,294 absorption. The public summary does not fully document its property eligibility, boundary or underlying vendor; do not transfer the occupancy rate to all rental houses.
- MMG Q3-labeled pipeline, dataset assembled August 19, 2026: Versa and Mural Brownsburg project rows; statuses and forecasts are a diligence list, not current availability. Initial summary counters display zero despite populated rows and are not used.
- Indiana DLGF April 15, 2026 Budget 101 presentation: gross-assessed-value tax cap categories, including 1% homestead and 2% rental/farmland; caps are not quoted tax rates or purchase-price formulas
- Boone County auditor: Indiana tax-cap categories and voter-approved referendum taxes outside the caps; obtain the actual parcel classification and tax-district computation
- DLGF taxpayer calculators: tax-district, assessed-value and deduction inputs; estimates are projections, not statements of true liability
- Indianapolis landlord registry: residential rental registration, with excluded-city exception; separate short-term-rental program
- Zillow all-home, all-bedroom, smoothed, seasonally adjusted metro ZORI CSV; observation 2026-09-30; retrieved 2026-10-21T03:09:00.655Z UTC
- Zillow repeat-rent methodology
- Census July 2023 metro delineations
- Zillow county-to-metro crosswalk, retrieved 2026-10-19
Geography and comparable populations
The July 2023 official metro includes Tipton County and excludes Putnam County. Zillow’s undated crosswalk instead includes Putnam and omits Tipton, using the older Indianapolis-Carmel-Anderson name. The rent index retains the provider geography; no county series is substituted. Official CBSA: 26900; separate Zillow RegionID: 394705. County and city figures are useful local checks but cannot reproduce this metro index.
| County | State | Zillow crosswalk |
|---|---|---|
| Boone County | IN | Included |
| Brown County | IN | Included |
| Hamilton County | IN | Included |
| Hancock County | IN | Included |
| Hendricks County | IN | Included |
| Johnson County | IN | Included |
| Madison County | IN | Included |
| Marion County | IN | Included |
| Morgan County | IN | Included |
| Shelby County | IN | Included |
| Tipton County | IN | Not included |
What the rent index measures
ZORI follows repeat asking-rent changes, weights toward the rental stock and smooths observations. It does not measure every signed lease, concessions, a two-bedroom quote, property income or a voucher payment standard. Broker apartment surveys have their own boundaries and property populations. Their vacancy and effective-rent readings are labeled by period and are never averaged into ZORI.
The headline and historical chart use one validated version. The file contains 740 metro rows; 740 have a latest-month observation. These are market counts, not rental-unit sample sizes; Zillow does not supply underlying unit sample counts here. Missing observations remain missing and prior months may be revised.
Refresh and editorial review
Provider Last-Modified: Fri, 16 Oct 2026 01:56:12 GMT. This page serves the committed last-good snapshot. The shared weekly refresh publishes validated versions atomically and retains the previous version on failure. Changed interpretation is flagged for review; imports do not advance the editorial review date. Local broker studies and photographs retain their own dates.
SHA-256: cf1ac2ab12236da3e05a81d06542e6fb95581704c6e9f375424e73b72ccb444b
Investment judgments are RentalCalcs’ analysis of the stated evidence. Purchase examples are explicitly assumed underwriting cases, not listings, appraisals, financing quotes or observed market cap rates. Report a correction.